
VA Mortgage Rates Near Me: What Veterans Need to Know Before They Buy
If you’re searching for VA mortgage rates near me, here’s a quick snapshot of where rates stand right now and what to expect:
| Loan Type | Average Rate (July 2026) | APR | Est. Monthly Payment* |
|---|---|---|---|
| 30-Year Fixed VA | 6.09% | 6.37% | $2,003 |
| 30-Year Fixed Conventional | 6.87% | 7.11% | Higher |
| 30-Year Fixed VA (Jul 30, 2026) | 6.34% | — | — |
*Based on a $350,000 mortgage.
VA loan rates consistently run lower than conventional rates — by nearly a full percentage point in July 2026. That gap can mean thousands of dollars saved over the life of your loan.
A few things to know upfront:
- No down payment required for eligible veterans and service members
- No private mortgage insurance (PMI) — ever
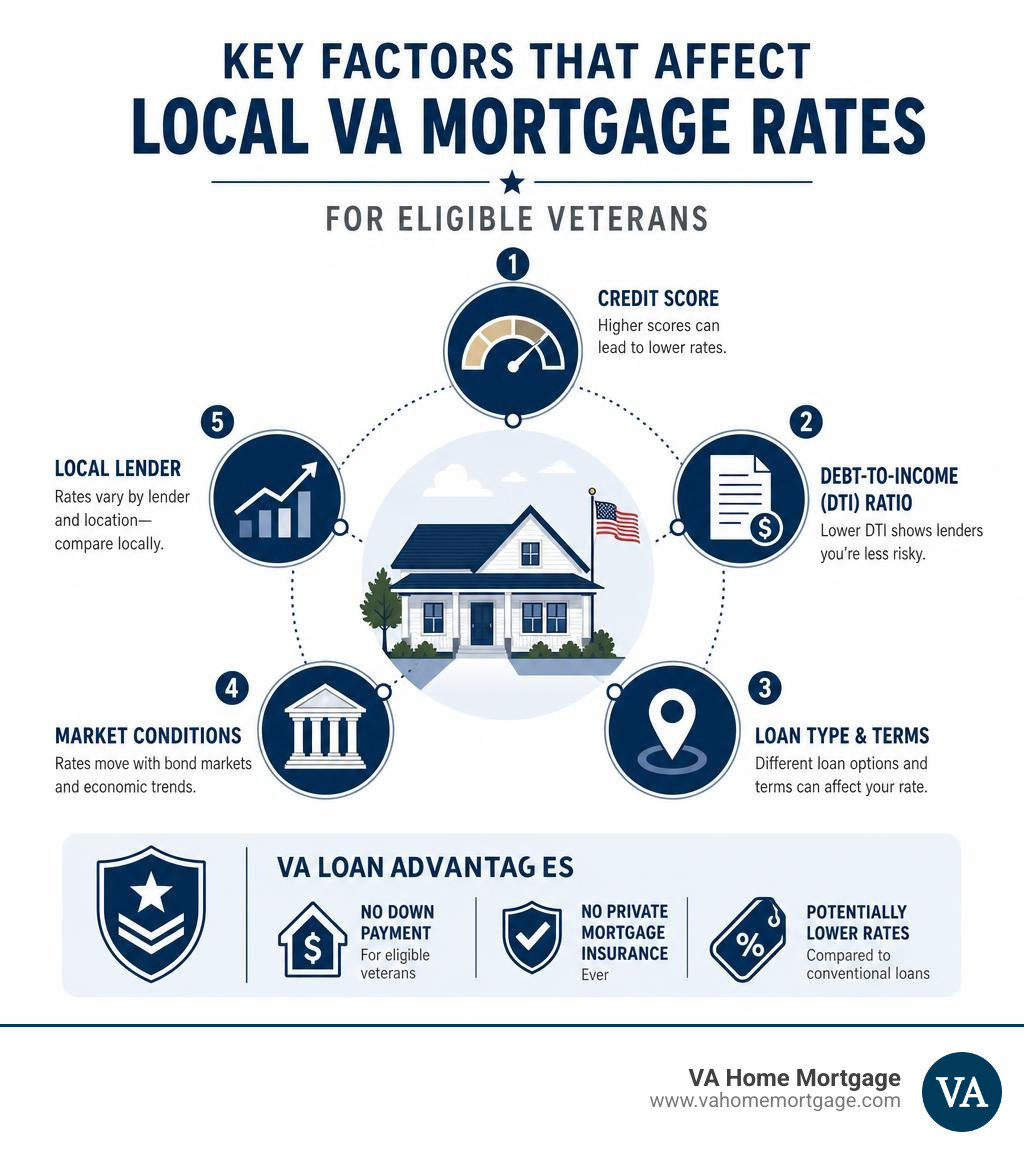
- Rates fluctuate daily based on bond markets and economic conditions
- Your personal rate depends on your credit score, debt-to-income (DTI) ratio, and the lender you choose
- Local lenders may offer different rates, so comparing options in your area matters
VA loan rates have largely moved between 6% and 7% over the past year and a half, making right now a reasonable window to explore your options — especially compared to conventional financing.
I’m Dale Gremillion, a Senior Loan Officer and Producing Branch Manager with over 25 years of experience helping veterans navigate VA mortgage rates near me and find financing strategies that fit their real lives. I’ll walk you through everything you need to compare local VA lenders and lock in the best rate available to you.
Understanding Current VA Mortgage Rates Near Me
When searching for va mortgage rates near me, it helps to look at recent national benchmarks to see where the housing market stands. Rates move continuously, but evaluating overall baseline numbers gives you a clear baseline before you begin requesting customized quotes from lenders.
In July 2026, the overall average rate for a VA loan settled around 6.05%, while conventional 30-year fixed mortgages averaged 6.87%. On individual trading days late in the month—such as July 30, 2026—the average 30-year fixed VA rate locked in at 6.34%. With an average rate of 6.09% and an APR of 6.37%, a veteran financing a home with a $350,000 mortgage sees a principal and interest monthly payment of approximately $2,003.
Over the past year and a half, interest rates for VA home loans have largely oscillated within a predictable 6% to 7% bracket. While macroeconomic shifts cause short-term rate volatility, VA loans have consistently maintained an advantageous pricing spread over non-government loans.
| Mortgage Loan Term / Type | Benchmark Interest Rate | Average APR | Monthly Payment ($350k Loan) |
|---|---|---|---|
| 30-Year Fixed VA Loan | 6.09% | 6.37% | $2,003 |
| 15-Year Fixed VA Loan | 5.35% | 5.72% | $2,831 |
| 30-Year Fixed Conventional | 6.87% | 7.11% | $2,298 |
| 30-Year Fixed FHA Loan | 6.25% | 7.02% | $2,154 |
Comparing loan options over time shows why military borrowers benefit from government backing: even when broader market rates push higher, VA pricing offers significant long-term savings. You can analyze current benchmark trends through external financial analysis like Compare Current VA Loan Rates to see how national pricing translates to your wallet.
Factors Determining Local VA Mortgage Rates
Understanding why mortgage rates fluctuate daily—and why two military borrowers down the street from each other might get quoted different numbers—requires looking under the hood of mortgage economics.
Mortgage interest rates are primarily driven by secondary financial markets. Lenders do not set rates out of thin air; rather, VA mortgage pricing closely mirrors the movement of 10-Year U.S. Treasury yields and Mortgage-Backed Securities (MBS). When investor demand for MBS rises, yields fall, and retail mortgage interest rates adjust downward. Conversely, inflation pressures or shifts in Federal Reserve policy push yields higher, driving up baseline consumer rates.
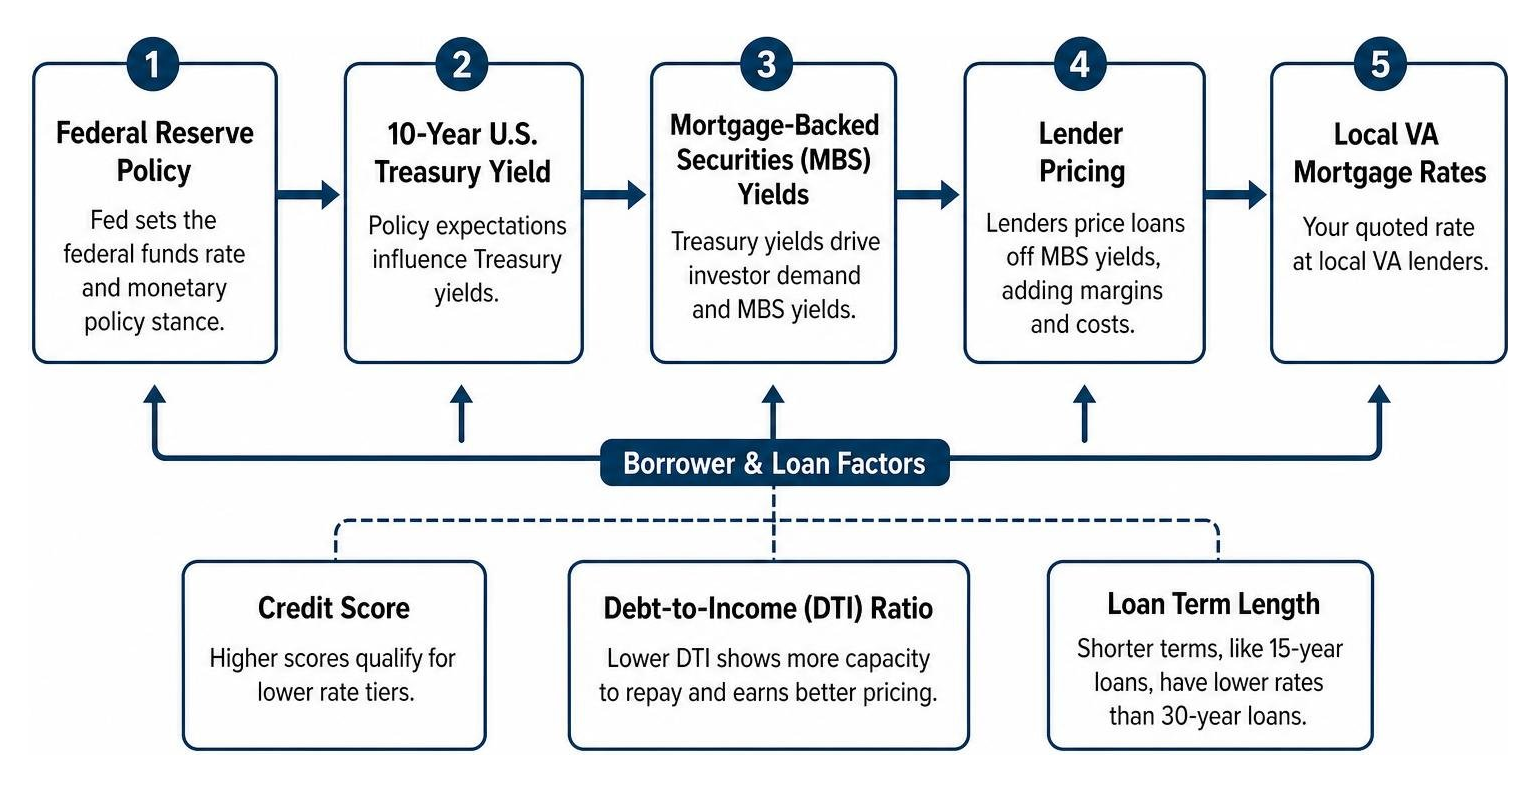
Beyond nationwide financial indicators, your personal borrower profile determines where your final loan offer lands within a lender’s rate tier structure:
- Credit Score: While the Department of Veterans Affairs does not set a mandatory minimum credit score, private lenders establish minimum benchmarks (typically starting around 620). Higher credit scores qualify you for lower interest rate tiers.
- Debt-to-Income (DTI) Ratio: Your total monthly debt payments divided by your gross monthly income gives lenders insight into your capacity to handle a mortgage payment. Lower DTI ratios generally command preferred interest pricing.
- Loan Term Length: Shorter terms, such as a 15-year fixed loan, carry lower interest rates than traditional 30-year terms because the lender takes on market duration risk for half the time.
- Rate Lock Timing: Daily rate volatility means timing matters. Locking your rate protects you from upward market spikes while your loan moves through processing and underwriting.
How to Compare VA Mortgage Rates Near Me Options
When shopping for va mortgage rates near me, comparing quotes isn’t as simple as glancing at the big headline interest rate. You need to look at the total financial picture by comparing loan estimate documents line by line.
Every formal mortgage application provides a standard Loan Estimate form that outlines the Annual Percentage Rate (APR), closing fees, and upfront loan costs. While the interest rate calculates your monthly principal and interest payment, the APR reflects the total cost of borrowing by bundling interest alongside lender origination charges and financing fees.
When evaluating local loan quotes, keep these elements in mind:
- Lender Origination Fees: Different lenders charge varying administrative, processing, and underwriting fees.
- VA Funding Fee: A standard statutory fee applied to VA loans to protect the guarantee program. It can be paid upfront or rolled directly into your loan balance. Disabled veterans with service-connected disabilities are generally exempt from this fee.
- Discount Points: Lenders may offer you the option to pay upfront cash points at closing to permanently buy down your interest rate.
- Direct Authority: Working with a direct VA lender with in-house underwriting streamlines approvals and prevents unexpected third-party delays or fee markups.
For more deep-dive comparisons on loan structures, check out our expert market breakdown on our official Blog.
Eligibility and Key Requirements for Local VA Loans
Before securing competitive local VA rates, you must confirm your basic military eligibility. The VA home loan program is designed for active-duty service members, Military Guard and Reserve members, and honorably discharged veterans.
To establish your authorization, you will need a Certificate of Eligibility (COE). We can pull your COE directly through the Department of Veterans Affairs portal in minutes, saving you time during pre-approval. Basic service minimums generally require:
- 90 continuous days of active service during wartime
- 181 continuous days of active service during peacetime
- 6 years of service in the National Guard or Selected Reserve
- Being a surviving spouse of a service member who died in the line of duty or from a service-connected disability
The defining feature of a VA home purchase loan is zero down payment requirement. While conventional loans typically require anywhere from 3% to 20% down to secure reasonable terms, eligible military home buyers can purchase a primary residence with $0 down without incurring additional risk surcharges.
Credit Score and Debt-to-Income (DTI) Standards
A common misconception among military buyers is that the government lends money directly or sets strict credit score rules. In reality, private lenders issue the loan, and the government guarantees a portion of it against default.
Because of this structure, individual mortgage companies set their own internal guidelines, known as lender overlays. While the government doesn’t set a baseline credit requirement, most institutions look for a minimum credit score of 620. However, borrowers with credit scores slightly below this benchmark can still qualify if compensating financial factors exist.
When evaluating your DTI ratio, traditional guidelines prefer a debt benchmark around 41%. However, because our direct underwriting evaluates full profile strength, military buyers with strong residual income, solid work stability, or substantial cash savings can often receive approval with DTI ratios reaching higher thresholds—sometimes up to 65% depending on overall scenario strength.
Special Local Programs and Financing Options
Local housing conditions require versatile mortgage options. Depending on whether you are buying an existing home, building custom property, or purchasing in competitive markets where median existing-home prices reach around $440,600, tailoring your financing structure makes a substantial difference.
We provide dedicated military loan programs designed to meet different homeownership goals:
- VA Purchase Loans: standard financing for single-family homes, townhomes, or approved condominiums with $0 down payment.
- VA Construction Financing: For buyers building ground-up residential properties, specialized programs streamline land acquisition and home construction. Discover how specialized options function by reading about Texas VA One Time Close Construction Loans to see how single-closing programs eliminate double closing costs.
- VA Native American Direct Loan (NADL): Specialized financing for eligible Native American veterans purchasing homes on federal trust land.
Explore our dedicated VA Home Mortgage resources to learn more about how tailored mortgage programs work for military families.
Evaluating Pros, Cons, and Local Refinancing Opportunities
Evaluating va mortgage rates near me requires weighing the broad financial benefits of VA loans against prospective upfront costs. For the vast majority of veterans, the savings provided by government-backed lending far outweigh standard conventional loans.
Benefits vs. Drawbacks of VA Home Financing
Pros:
- Zero Down Payment: Purchase a home up to localized loan limits without putting cash down.
- No Monthly PMI: Unlike FHA or conventional loans with less than 20% down, VA loans never require monthly mortgage insurance premiums.
- Lower Base Interest Rates: Average VA interest rates consistently undercut conventional mortgage rates by 0.50% to 0.80%.
- Flexible Credit and DTI Guidelines: Government backing allows lenders to extend financing to military families with less-than-perfect credit profiles.
- Limitation on Closing Costs: The VA strictly regulates the types of fees and administrative charges lenders can levy against veteran buyers.
Cons:
- VA Funding Fee: A one-time statutory fee charged to maintain the program for future generations. (Though exempt for disabled veterans).
- Primary Residence Limitation: VA loans cannot be used to purchase investment properties or secondary vacation homes.
- Occupancy Requirements: Borrowers must certify intent to occupy the property as their primary home within 60 days of closing.
When to Secure Lower VA Mortgage Rates Near Me Through Refinancing
If you already own a home with a VA mortgage, staying up to date on va mortgage rates near me allows you to identify ideal windows to refinance your current loan and cut monthly housing costs.
When interest rates drop or your credit score improves significantly, refinancing can yield thousands in interest savings over your remaining loan term. Two primary refinance structures serve veteran homeowners:
- Interest Rate Reduction Refinance Loan (IRRRL): Often called the VA Streamline Refinance, this streamlined option allows you to replace your current interest rate with a lower market rate with minimal paperwork, no home appraisal, and no income verification in most cases.
- VA Cash-Out Refinance: Converts built-up home equity into liquid funds to payoff high-interest debt, fund home renovations, or cover personal costs while refinancing your main mortgage into a new term.
For an exhaustive step-by-step walkthrough of streamline options and calculation strategies, review The Ultimate Guide to VA Home Mortgage Refinancing.
Frequently Asked Questions About VA Loan Rates
Why are VA mortgage rates lower than conventional loan rates?
VA mortgage rates run lower than conventional loan rates because the U.S. Department of Veterans Affairs guarantees up to 25% of the loan value against default. This federal safety net reduces financial loss risks for private lenders. Because mortgage lenders face significantly less default risk when funding military home loans, they pass those risk-mitigation savings directly to veteran borrowers in the form of lower base interest rates and flexible loan underwriting rules.
What credit score is needed to qualify for the best VA mortgage rate?
While the VA does not establish a statutory minimum credit score, most private mortgage lenders enforce an internal benchmark threshold of 620. To qualify for the lowest tier VA mortgage rates available, lenders typically look for credit scores of 720 or higher. However, because VA underwriting prioritizes your complete financial picture—including residual income and stable employment history—borrowers with credit scores in the mid-600s still secure highly competitive interest rates compared to conventional loan options.
How does a mortgage rate lock work during the home buying process?
A mortgage rate lock is a formal agreement between you and your mortgage lender that guarantees a specific interest rate for a designated timeframe—typically 30, 45, or 60 days—while your mortgage application undergoes processing and underwriting. Locking your rate shields you from market volatility and sudden rate spikes while your deal progresses toward closing. If market rates rise during your lock period, your guaranteed rate remains unchanged.
Conclusion
Finding competitive va mortgage rates near me isn’t just about looking at general online benchmarks—it’s about partnering with a direct VA mortgage lender who understands veteran financing inside and out.
At Capital Home Mortgage, we operate as a direct VA loan authority featuring fast in-house underwriting, personalized pre-approvals, and dedicated service tailored to military families. By cutting out third-party middlemen, we deliver rapid closings and low interest rate options with $0 down and $0 ongoing PMI.
Ready to compare exact rate quotes or lock in your military loan benefit? Connect directly with our knowledgeable team at VA Home Mortgage Team or get started on your home purchase or refinance journey today by visiting Explore Local VA Financing Options Today.


