
What Veterans Need to Know About VA Mortgage Rates on Jumbo Loans in 2026
VA mortgage rates on jumbo loans are significantly lower than conventional jumbo rates right now — and if you’re a veteran buying a high-value home, that gap could save you tens of thousands of dollars over the life of your loan.
Here’s a quick comparison of where rates stand as of August 2026:
| Loan Type | Average 30-Year Fixed Rate |
|---|---|
| VA loan (all balances) | 6.49% |
| Conventional jumbo loan | 6.81% |
| FHA loan | 6.38% |
| 15-year fixed jumbo | 6.26% |
That 0.32% difference between VA and conventional jumbo rates may not sound like much. But on a $1,000,000 loan, it adds up to thousands of dollars per year in interest savings — before you even factor in the VA’s zero-down-payment benefit and no private mortgage insurance requirement.
The key facts at a glance:
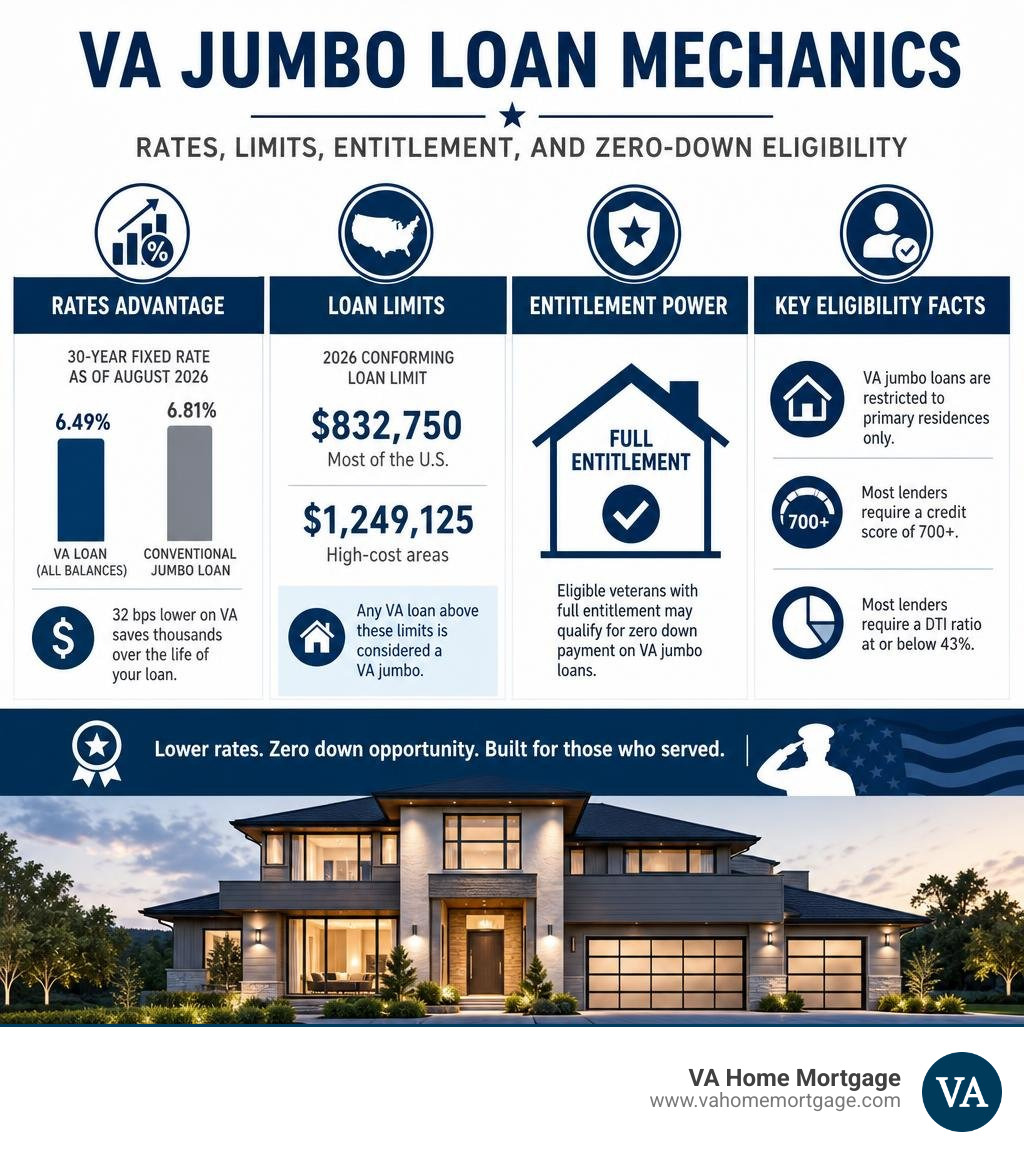
- The 2026 conforming loan limit is $832,750 for most of the U.S. (up to $1,249,125 in high-cost areas)
- Any VA loan above these limits is considered a VA jumbo (also called a high-balance VA loan)
- Eligible veterans with full entitlement may still qualify for zero down payment on VA jumbo loans
- VA jumbo loans are restricted to primary residences only
- Most lenders require a credit score of 700+ and a DTI ratio at or below 43%
I’m Dale Gremillion, Senior Loan Officer and Producing Branch Manager at Capital Home Mortgage, a direct VA lender with over 25 years of experience helping veterans navigate complex financing — including VA mortgage rates on jumbo loans for high-value home purchases. In this guide, I’ll walk you through exactly how VA jumbo loans work, what they cost, and how to get the best rate available to you.
Comparing VA Mortgage Rates Jumbo Loan Options to Standard High-Balance Financing
When you enter high-value real estate markets, conventional jumbo loans traditionally come with strict hurdles. Conventional jumbo options usually demand down payments of 10% to 20%, stringent reserve requirements, and elevated pricing adjustments. However, when evaluating competitive va mortgage rates jumbo loan scenarios, military borrowers enjoy a distinct pricing edge.
As of August 2026, the national average 30-year fixed rate for a conventional jumbo mortgage sits at 6.81%. In contrast, the national average 30-year fixed VA mortgage interest rate stands at 6.49%. On a $1,000,000 loan amount, that 32-basis-point discount translates directly into roughly $210 per month in interest savings alone—or more than $75,000 over the 30-year life of the loan.
To understand how high-balance financing options stack up side by side, review the comparison below:
| Loan Feature | VA Jumbo Loan | Conventional Jumbo Loan | Conventional 80/10/10 Piggyback |
|---|---|---|---|
| Average Interest Rate | 6.49% | 6.81% | 6.81% (1st) / 8.50%+ (2nd HELOC) |
| Minimum Down Payment | 0% (with full entitlement) | 10% – 15% | 10% cash down |
| Mortgage Insurance (PMI) | None | None (if 20% down) or Monthly PMI | None |
| Min. Credit Score | 680 – 700+ (lender overlay) | 700 – 720+ | 700+ |
| Max Debt-to-Income (DTI) | 43% (flexible with residual income) | 43% | 43% |
| Cash Reserves Required | 2 to 12 months | 6 to 12 months | 6 to 12 months |
As shown in the table, choosing a VA jumbo loan eliminates the need to execute complicated “piggyback” loan structures (where a buyer takes an 80% primary conforming mortgage paired with a 10% second mortgage or HELOC and 10% cash down). Bypassing those extra closing fees and higher second-mortgage interest rates saves veterans significant money at the closing table. You can check current pricing trends on our Rates Test Page.
How Entitlement Affects VA Mortgage Rates Jumbo Loan Thresholds
Understanding entitlement is critical to unlocking competitive high-balance financing without putting money down. Every eligible veteran receives primary entitlement backed by the U.S. Department of Veterans Affairs.
For 2026, the standard single-family conforming loan limit baseline established by the Federal Housing Finance Agency (FHFA) is $832,750. In high-cost counties across the United States, this conforming baseline expands up to $1,249,125.
Here is how entitlement directly shapes your loan terms:
- Full Entitlement: Thanks to the passage of the Blue Water Navy Vietnam Veterans Act, if you have full VA entitlement (meaning you do not currently have an active VA loan or have fully restored your entitlement), there is no statutory VA loan limit. This means we can offer zero-down-payment financing on purchase prices exceeding $1,000,000 or $2,000,000, subject strictly to income and credit underwriting.
- Partial Entitlement: If you currently have an active VA loan on another property or previously defaulted on a VA loan without full repayment, you hold partial entitlement. In this scenario, the standard county conforming loan limit ($832,750 or up to $1,249,125) acts as a strict cap. If your target purchase price exceeds your remaining VA guarantee threshold, you will simply pay a 25% down payment on the difference between the purchase price and your available entitlement limit.
For instance, if you have partial entitlement capped at $832,750 and purchase a home for $1,032,750, the unbacked amount is $200,000. Your required down payment is 25% of that excess, which equals $50,000—still drastically lower than the $100,000 to $206,000 required by standard conventional jumbo lenders!
Underwriting and Qualification Standards for High-Balance VA Loans
Because VA jumbo loans involve larger capital outlays, mortgage underwriters review high-balance loan applications with greater attention to risk mitigation. While the VA government guarantee reduces lender exposure, financial institutions apply prudent underwriting overlays on higher loan balances.

When applying for high-balance VA financing, you should prepare to meet these specific underwriting benchmarks:
- Credit Score Standards: While standard VA guidelines technically do not mandate a minimum credit score, high-balance jumbo VA financing typically requires a middle credit score of 700 or higher to secure the lowest va mortgage rates jumbo loan tiers. Some specialized programs accept scores down to 680, but maintaining a score above 700 ensures optimal pricing.
- Debt-to-Income (DTI) Ratios: Lenders generally cap a borrower’s total debt-to-income ratio at 43%. This calculation includes your proposed principal, interest, taxes, insurance, home association dues, and all recurring debt obligations relative to gross monthly income.
- Cash Reserve Requirements: Unlike baseline VA loans which often demand zero cash reserves after closing, high-balance VA loans require verified liquid assets. Expect underwriters to ask for 6 to 12 months of full monthly mortgage payments (PITI) sitting in liquid accounts after accounting for all closing costs. Liquid reserves can include savings accounts, checking accounts, money market funds, vested stocks, and qualified retirement accounts (like 401ks or IRAs).
- VA Residual Income: High-balance underwriting heavily emphasizes VA residual income analysis. Residual income measures the actual discretionary cash remaining after paying all monthly debts, taxes, and housing costs. High-balance approvals frequently require residual income calculations that exceed standard VA regional threshold minimums by 20% or more.
Occupancy Rules and Eligibility Criteria for a VA Mortgage Rates Jumbo Loan
A core mandate of the Department of Veterans Affairs loan program is expanding homeownership opportunities for military families. Consequently, VA loans—including high-balance jumbo loans—are legally restricted to primary residences only.
Key occupancy and property criteria include:
- Primary Residence Certification: Borrowers must sign an occupancy affidavit certifying that they intend to occupy the home as their primary residence within 60 days of loan closing.
- Prohibition on Second Homes & Investment Properties: You cannot use a VA jumbo loan to buy a vacation home, secondary property, or dedicated investment rental.
- Multi-Unit Properties: You can utilize a VA jumbo loan to purchase a multi-unit property (up to a 4-unit residential building), provided you occupy one of the units as your primary residence. When purchasing multi-unit properties, potential rental income from non-occupied units can sometimes be factored into underwriting if lease documentation or appraisal market rent analyses support it.
To explore specific property qualification guidelines and local military lending criteria, visit our detailed guides in the VA Home Mortgage Category.
The VA Funding Fee Structure for Jumbo Loan Balances
The VA funding fee is a mandatory statutory fee charged by the Department of Veterans Affairs to sustain the loan guarantee program for future generations. One major advantage of high-balance VA loans is that the funding fee percentage is calculated on the total loan amount—it does not jump to higher rates simply because your loan enters jumbo balance territory.
The funding fee amount depends on whether you have used your VA loan benefit previously and your total down payment percentage:
- First-Time Use (0% Down Payment): 2.15% of the total loan amount.
- Subsequent Use (0% Down Payment): 3.30% of the total loan amount.
- Down Payment of 5% to 9.9%: Reduced to 1.50% (applies to first-time and subsequent use).
- Down Payment of 10% or More: Reduced to 1.25% (applies to first-time and subsequent use).
Note: Borrowers can choose to pay the VA funding fee in cash at closing or roll the fee directly into the total loan balance.
Funding Fee Exemptions
Many veterans qualify for a complete exemption from the VA funding fee. You are exempt from paying this fee if you meet any of the following criteria:
- You receive VA compensation for a service-connected disability.
- You are eligible to receive disability compensation but receive active-duty retirement pay instead.
- You are a surviving spouse of a veteran who died in service or from a service-connected disability.
- You are an active-duty service member who has been awarded the Purple Heart.
For a veteran obtaining a $1,100,000 loan balance, an exemption saves $23,650 to $36,300 in upfront financing fees right out of the gate!
Key Advantages and Cost Savings of VA Jumbo Financing
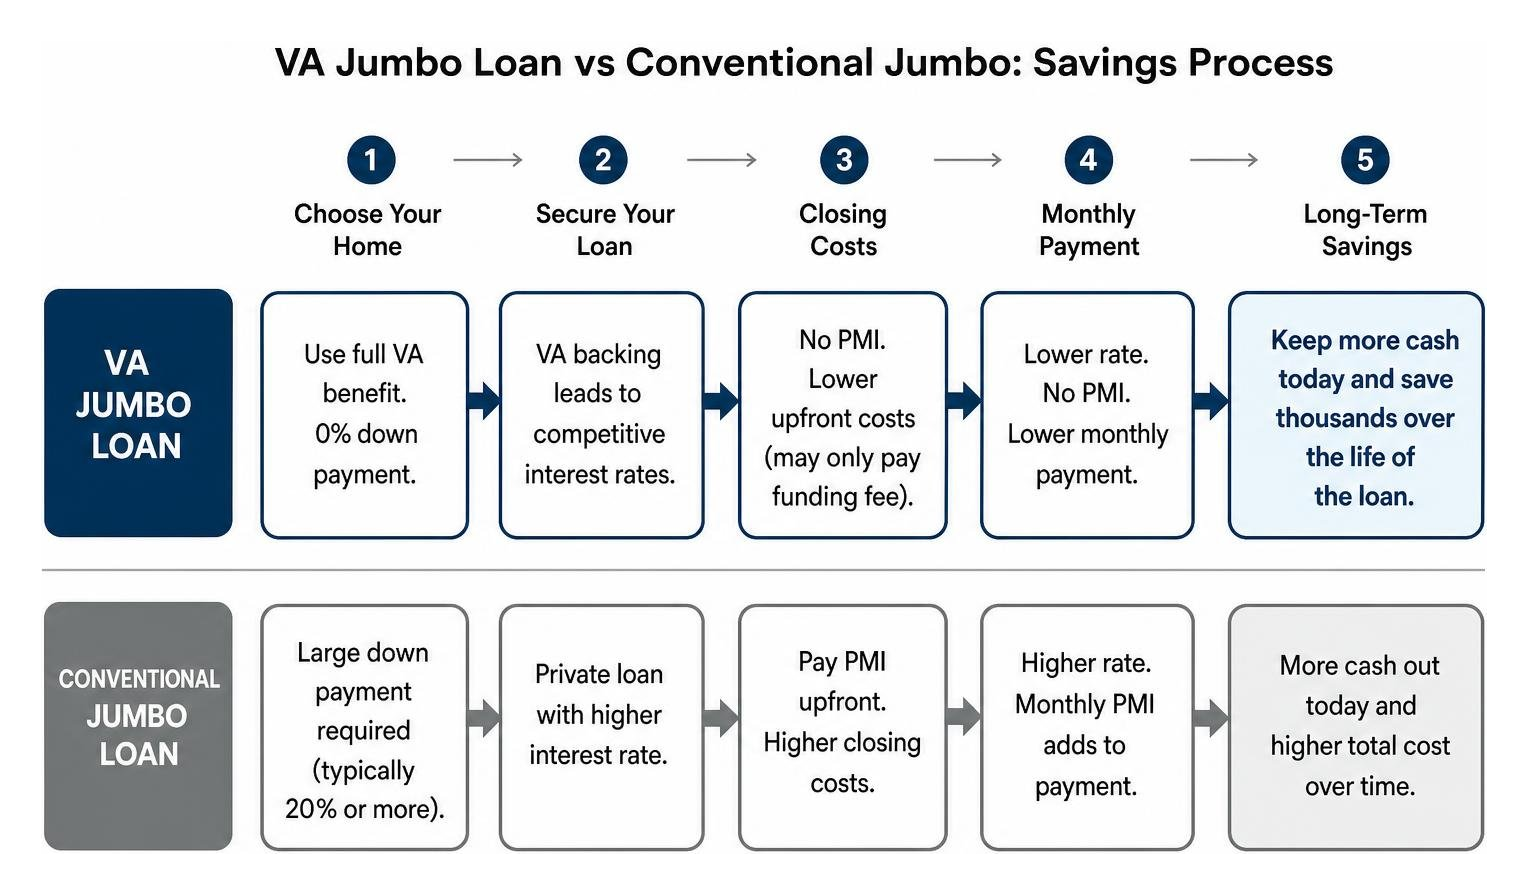
Choosing a high-balance VA mortgage over conventional jumbo products delivers long-term financial benefits. Beyond securing competitive va mortgage rates jumbo loan terms, military families avoid significant capital outlays at closing and throughout the life of the loan.
Here are the primary advantages of utilizing high-balance VA financing:
- Zero Required Down Payment: Preserve your personal cash reserves and liquid wealth for investments, emergencies, or business opportunities rather than tying up hundreds of thousands of dollars in real estate equity.
- No Private Mortgage Insurance (PMI): Conventional borrowers who put down less than 20% on high-value homes face costly monthly private mortgage insurance charges. High-balance VA loans never require PMI, saving borrowers hundreds of dollars every month.
- Below-Market Interest Rates: Because the federal government guarantees a portion of every VA loan, lenders face lower default risk. We pass those risk savings directly to borrowers through lower baseline interest rates compared to private jumbo products.
- Flexible Prepayment Terms: VA high-balance loans carry no prepayment penalties. You can make extra principal payments, pay off your loan early, or refinance down the road without financial penalties.
- Streamlined Refinance Options: If interest rates drop in future economic cycles, you can refinance your jumbo VA mortgage using the Interest Rate Reduction Refinance Loan (IRRRL) program, requiring minimal documentation and often no appraisal.
To stay updated on housing trends, savings strategies, and military financial planning tips, explore our active Blog.
Frequently Asked Questions About VA Jumbo Mortgages
Can I get a VA jumbo loan with zero down payment?
Yes, absolutely. If you have full VA entitlement, you can qualify for a zero-down-payment VA jumbo loan regardless of whether the purchase price is $900,000 or $1,500,000+. The passage of the Blue Water Navy Vietnam Veterans Act eliminated maximum loan limits for full entitlement holders. However, you must still satisfy lender underwriting criteria, including credit score minimums (typically 700+), debt-to-income requirements (43% max), and residual income tests to qualify for zero-down approval.
Are VA jumbo loan interest rates higher than standard VA loan rates?
Generally, no! Unlike conventional mortgage markets where jumbo loans frequently carry pricing markups due to secondary market liquidity constraints, VA mortgage rates remain exceptionally stable across loan sizes. At Capital Home Mortgage, our direct VA lending authority allows us to offer competitive interest rates on high-balance VA loans that closely track standard VA rates—frequently delivering average 30-year fixed rates around 6.49%, well below conventional jumbo averages of 6.81%.
What cash reserves are required for a high-balance VA loan?
For high-balance or VA jumbo loans exceeding standard conforming loan limits ($832,750 in most areas), lenders typically require cash reserves equal to 6 to 12 months of full monthly housing payments (Principal, Interest, Taxes, and Insurance). Reserves must be verified liquid or semi-liquid assets remaining in your accounts after paying your earnest money deposit and closing costs.
Conclusion
Navigating high-value home purchases requires specialized mortgage expertise. When comparing va mortgage rates jumbo loan scenarios, military borrowers quickly realize that VA high-balance loans offer an unbeatable combination of zero down payment options, competitive interest rates, and no monthly mortgage insurance.
At Capital Home Mortgage, we are proud to serve those who served. As a direct VA mortgage lender with in-house underwriting, we deliver fast decisions, streamlined processing, and direct authority to approve high-balance VA loans efficiently. Whether you are purchasing a luxury primary residence or refinancing an existing high-balance property, our team is here to guide you every step of the way.
Ready to explore your personalized rate quotes and loan options? Check out our live market updates on Rates Test Page 2 or get in touch directly with our experienced specialists by visiting the VA Home Mortgage Team.


