
Why Finding a VA Mortgage Near Me Starts With Knowing Your Options
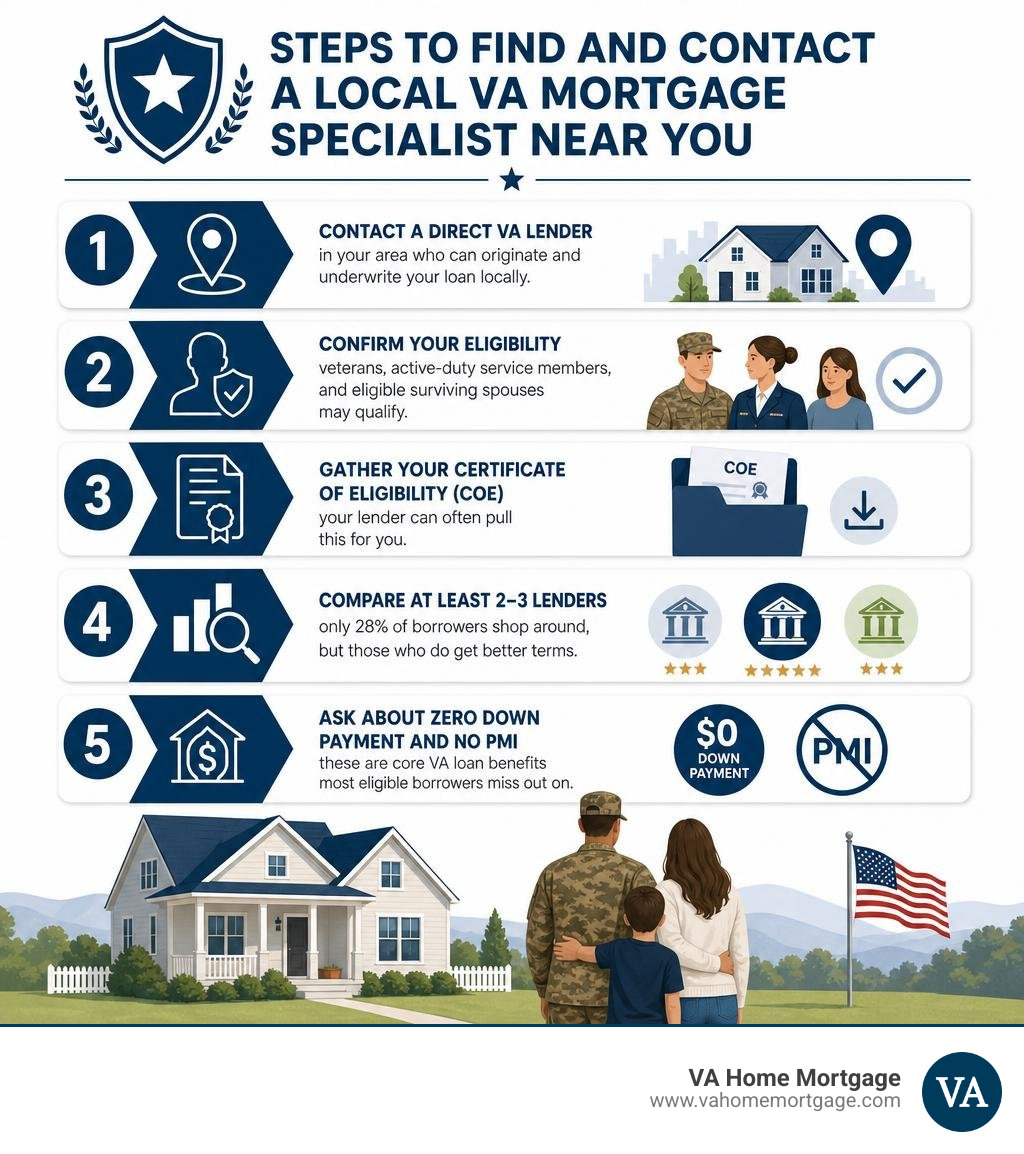
If you’re looking for a VA mortgage near me, here’s a quick-start guide to finding a local VA home loan specialist:
- Contact a direct VA lender in your area (like VA Home Mortgage) who can originate and underwrite your loan locally
- Confirm your eligibility — veterans, active-duty service members, and eligible surviving spouses may qualify
- Gather your Certificate of Eligibility (COE) — your lender can often pull this for you
- Compare at least 2–3 lenders — only 28% of borrowers shop around, but those who do get better terms
- Ask about zero down payment and no PMI — these are core VA loan benefits most eligible borrowers miss out on
Since 1944, the VA Home Loan program has helped millions of veterans and service members become homeowners — often with no down payment and no private mortgage insurance. That’s a benefit most conventional borrowers can only dream about, since standard loans typically require a 20% down payment just to avoid PMI.
Yet finding the right local specialist to guide you through the process can feel overwhelming, especially with so many national lenders competing for your attention online.
This guide cuts through the noise. It shows you exactly how to find and contact a qualified local VA home loan representative, what to ask them, and how to make sure you’re getting the best deal available in your area.
I’m Dale Gremillion, Senior Loan Officer and Producing Branch Manager with over 25 years of residential mortgage lending experience, specializing in helping veterans and military families navigate the VA mortgage near me search and secure the right financing for their situation. I’ll walk you through everything you need to know to connect with the right local VA loan specialist and close with confidence.
Understanding the VA Home Loan Program and Eligibility Requirements
When you search for a va mortgage near me, it helps to understand what the Department of Veterans Affairs actually does—and what private lenders like us handle on the ground.
The VA itself doesn’t issue mortgages directly to buyers. Instead, the U.S. Department of Veterans Affairs provides a financial guaranty to approved private mortgage lenders. This government backing lowers the risk for lenders, enabling us to offer dramatically better terms, lower interest rates, and lenient credit standards compared to conventional financing.
To take advantage of this benefit, you must meet basic service eligibility requirements:
- Active-Duty Service Members: Typically eligible after serving 90 continuous days during wartime or 181 days during peacetime.
- Veterans: Eligibility depends on when you served, but generally requires 90 days of wartime service or 181 continuous days of peacetime service, with an honorable discharge.
- National Guard and Reserve Members: Eligible after 6 years of honorable service, or 90 days of active service under Title 10 or Title 32 orders.
- Eligible Surviving Spouses: Unremarried spouses of service members who died in the line of duty or as a result of a service-connected disability.
If you fit into one of these categories, you hold a key that unlocks one of the most powerful wealth-building tools in American real estate. Exploring our dedicated VA Home Mortgage resources will give you a deeper look into how these options work for your specific military history.
VA Loan Benefits: Zero Down Payment and No PMI
The main reason military buyers actively look for a va mortgage near me comes down to two major financial advantages: zero down payment and no mandatory private mortgage insurance (PMI).
In the conventional mortgage world, home buyers are typically expected to put down 20 percent of the purchase price to secure competitive interest rates and avoid costly monthly PMI fees. On a $400,000 home, a 20 percent down payment equals $80,000 in cash required upfront at closing. For many hard-working military families, saving that much cash while frequently moving across the country on active assignment is a massive hurdle.
With a VA loan guaranteed by the government:
- 0% Down Payment: Qualified borrowers can buy a home with zero down payment, preserving their hard-earned savings for moving expenses, furniture, or emergency funds.
- No Monthly PMI: Conventional borrowers who put down less than 20 percent must pay monthly PMI, which can easily add $150 to $300 or more to their monthly payment without building any equity. VA loans eliminate PMI entirely.
- Competitive Interest Rates: Because of the government guaranty, VA interest rates are historically lower than conventional mortgage rates, giving you far more purchasing power in today’s 2026 housing market.
Certificate of Eligibility and Credit Score Criteria
Before a lender can approve your mortgage, we must verify your military service through an official document called the Certificate of Eligibility (COE). The COE tells us that you have sufficient entitlement available for a VA-guaranteed loan.
Obtaining your COE used to take weeks of mail exchanges, but today, direct VA lenders can log directly into the VA’s automated WebLGY portal and retrieve your certificate electronically in a matter of minutes.
While the government sets eligibility standards, the VA does not set a minimum credit score requirement for home loans. Instead, individual lenders set their own overlays. While traditional banks might demand credit scores of 620 to 660, flexible direct lenders can approve VA purchase loans for borrowers with credit scores down to 580—or even lower under specific manual underwriting conditions.
Lenders also evaluate your Debt-to-Income (DTI) ratio and residual income—a unique VA calculation that ensures you have enough income left over every month after paying your major bills to cover basic living expenses like groceries, gas, and healthcare.
How to Find and Contact a Qualified VA Mortgage Near Me
When beginning your search for a va mortgage near me, working with a lender that holds direct VA authority and in-house underwriting makes a world of difference.
A direct lender handles every stage of your mortgage under one roof: pre-approval, processing, property appraisal review, underwriting, and closing. This eliminates middleman delays, speeds up communication, and gives you direct access to the decision-makers reviewing your loan file.

Finding a VA Mortgage Near Me for In-Person or Regional Support
Many military buyers prefer local or regional loan representatives who understand the unique dynamics of their local housing market. Local loan officers know county loan limits, regional property tax rates, specific VA appraisal expectations in your immediate area, and local real estate agent networks.
To connect with an expert local representative:
- Look for lenders with regional offices in your state or local community.
- Reach out directly to a dedicated loan officer through our expert VA Home Mortgage Team page to schedule a face-to-face or virtual consultation.
- Check regional VA loan volume data published annually to verify that your lender actively specializes in VA originations rather than just offering them as an afterthought.
Having a dedicated local point of contact means you won’t get passed around to different call center operators every time you call with a time-sensitive question about your pre-approval letter.
Shopping Around and Comparing Local Lender Offers
Here is a striking industry statistic: according to a Zillow survey, only 28 percent of prospective homebuyers shop around for their mortgage. Nearly three out of four buyers accept the very first loan offer they receive!
By failing to compare loan offers, borrowers potentially leave tens of thousands of dollars on the table over the life of their mortgage. Even a tiny quarter-point difference in your interest rate can save you $50 to $100 per month on a standard home loan.
Here is a step-by-step framework to effectively shop around when searching for a va mortgage near me:
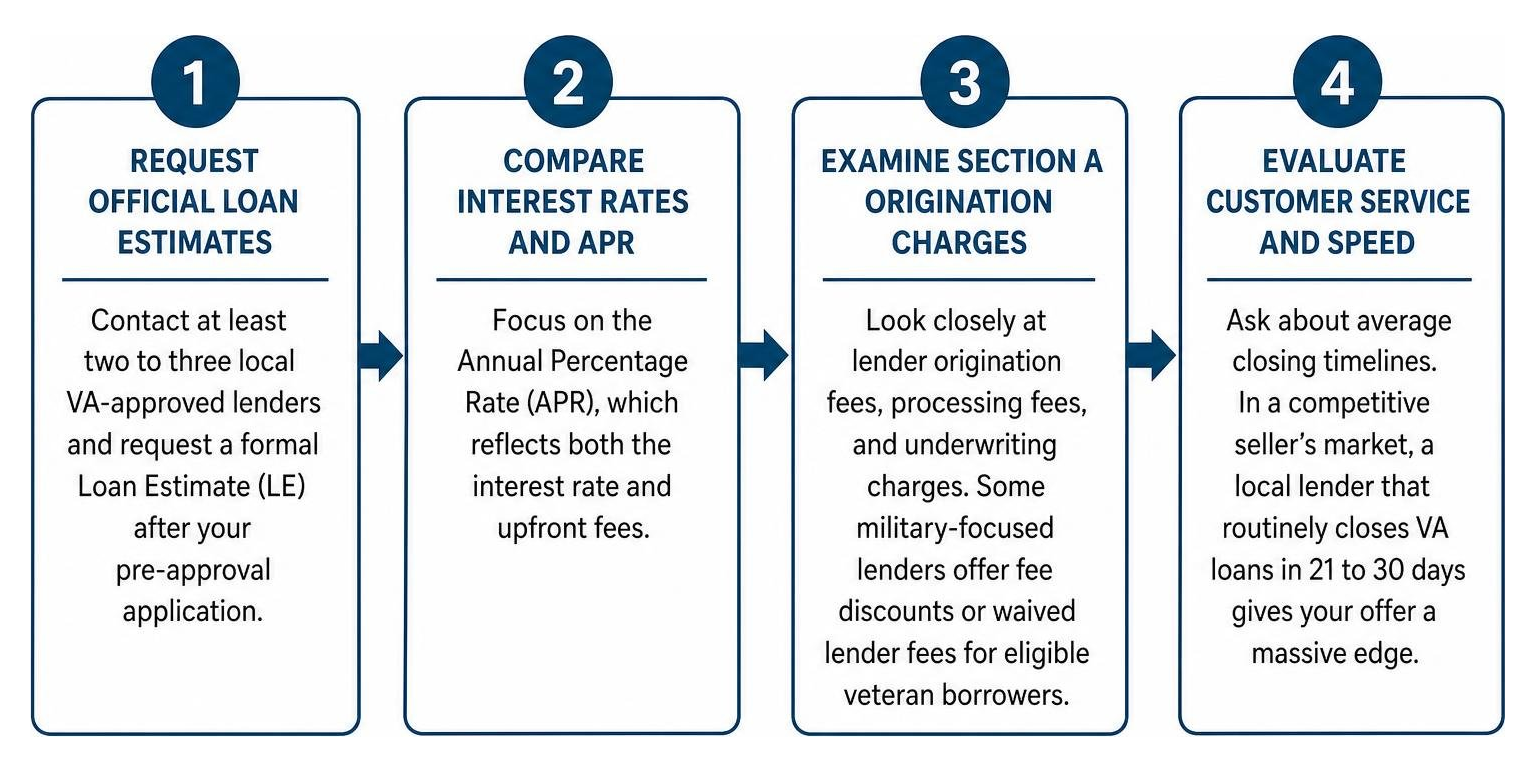
- Request Official Loan Estimates: Contact at least two to three local VA-approved lenders and request a formal Loan Estimate (LE) after submitting your pre-approval application.
- Compare Interest Rates and APR: Focus on the Annual Percentage Rate (APR), which reflects both the interest rate and upfront fees.
- Examine Section A Origination Charges: Look closely at lender origination fees, processing fees, and underwriting charges. Some military-focused direct lenders offer fee discounts or waived lender fees for eligible veteran borrowers.
- Evaluate Customer Service and Speed: Ask about average closing timelines. In a competitive seller’s market, a local lender that routinely closes VA loans in 21 to 30 days gives your offer a massive edge over slow online platforms.
The VA Home Loan Process and Key Financial Considerations
Understanding how a VA home loan works step-by-step empowers you throughout your homebuying journey:
- Initial Consultation & Application: Contact your local representative, submit basic financial documentation (W-2s, pay stubs, tax returns), and request your COE.
- Pre-Approval Issuance: Your lender verifies your income, assets, and credit to issue a formal pre-approval letter stating your maximum purchase power.
- House Hunting & Offer: You partner with a trusted real estate agent to find a home and submit a purchase contract with a VA financing contingency.
- VA Appraisal & Inspection: Once under contract, your lender orders an official VA appraisal to verify the home’s market value and ensure it meets VA Minimum Property Requirements (MPRs) for safety and structural soundness.
- Underwriting & Final Approval: In-house underwriters review the appraisal, title work, and verified financial files to issue a clear-to-close.
- Closing & Keys: You review and sign your final Closing Disclosure (CD), transfer any required closing funds, and receive the keys to your new home!
VA Purchase Loan vs. VA Cash-Out Refinance
Depending on whether you are buying a home or already own one, the VA program offers distinct mortgage pathways designed for different financial goals.
| Feature | VA Purchase Loan | VA Cash-Out Refinance | Interest Rate Reduction Refinance Loan (IRRRL) |
|---|---|---|---|
| Primary Goal | Buy a new home | Extract cash equity / Refinance non-VA loan | Lower interest rate or payment |
| Down Payment / Equity | 0% down payment required | Up to 90%-100% LTV depending on lender | No cash out allowed |
| Appraisal Required? | Yes, mandatory VA appraisal | Yes, mandatory VA appraisal | Usually no appraisal required |
| Income Verification | Full income/credit underwriting | Full income/credit underwriting | Streamlined (minimal documentation) |
| Occupancy Rule | Primary residence | Primary residence | Must certify prior primary occupancy |
If you currently hold a higher interest rate on your existing mortgage, a VA Cash-Out Refinance allows you to tap into your home’s equity to consolidate high-interest debt, pay for major home renovations, or handle unexpected expenses. Alternatively, if you already have a VA loan and simply want to lower your monthly interest rate, a VA IRRRL (Streamline Refinance) offers a fast, low-stress path without requiring a full appraisal or credit underwriting.
Understanding VA Loan Fees and Closing Costs
While VA loans eliminate down payments and PMI, borrowers should still budget for standard closing costs and the one-time VA Funding Fee.
The VA Funding Fee is a government-mandated fee paid directly to the Department of Veterans Affairs to sustain the loan guaranty program for future generations of military members. The fee ranges from 1.25% to 3.3% of the total loan amount, depending on your down payment size and whether you have used your VA loan benefit before.
Crucially, the VA Funding Fee can be rolled directly into your total loan balance, meaning you don’t need to pay it in cash at the closing table.
VA Funding Fee Exemptions: You are completely exempt from paying the VA Funding Fee if you meet any of the following criteria:
- You receive VA compensation for a service-connected disability.
- You are entitled to receive VA disability compensation but receive active-duty retirement pay instead.
- You are a surviving spouse receiving Dependency and Indemnity Compensation (DIC).
- You are an active-duty service member who has received the Purple Heart.
Beyond the funding fee, standard closing costs include title insurance, escrow reserves for property taxes and homeowners insurance, appraisal fees, and recording fees. Under VA guidelines, sellers are allowed to contribute up to 4% of the purchase price toward your closing costs and prepaid expenses!
For deeper dives into closing cost breakdowns and refinancing strategies, explore our latest military homebuying insights on our official Blog.
Frequently Asked Questions About Local VA Loans
What credit score do I need for a local VA mortgage near me?
While the Department of Veterans Affairs does not establish a official hard minimum credit score requirement, most mortgage lenders apply internal guidelines called overlays.
At Capital Home Mortgage, as a direct VA lender with in-house underwriting authority, we maintain flexible credit requirements and actively work with qualified borrowers starting at a 580 credit score threshold. If your credit history includes past hiccups or medical debts, our local specialists can evaluate your overall financial picture, debt-to-income ratio, and residual income to help you qualify or build a quick roadmap toward pre-approval.
What documents do local VA lenders provide during the application process?
When you begin working with a direct local VA mortgage specialist, we provide several standardized, transparent financial documents designed to protect you:
- Pre-Approval Letter: A formal document detailing your approved purchasing budget, demonstrating your strong buying power to sellers.
- Loan Estimate (LE): Standardized 3-page form delivered within three days of applying, detailing your projected interest rate, monthly payment, and itemized closing costs.
- Closing Disclosure (CD): Delivered at least three business days prior to closing, outlining your exact final terms and exact cash required to close.
- Quick Reference Guides & Checklists: Documents helping you organize required personal tax filings, W-2s, earnings statements, and military service documentation (DD-214 or Statement of Service).
How do I apply for a VA home loan with a local specialist?
Applying for a VA home loan with our local team is simple, straightforward, and can be completed online or over the phone:
- Initial Contact: Reach out directly through our portal or call a local loan representative.
- Submit Information: Provide basic identification, income proofs (recent pay stubs/W-2s), and bank statements.
- COE Retrieval: Give us permission to pull your official Certificate of Eligibility directly from the VA WebLGY system on your behalf.
- Underwriting Review: Our in-house underwriting team reviews your file locally, allowing us to issue a firm pre-approval letter quickly so you can start shopping for your dream home!
Conclusion
Searching for a va mortgage near me doesn’t have to be overwhelming. By partnering with a dedicated, direct VA lender that offers in-house underwriting, zero down payment financing, and local expertise, you can navigate the path to homeownership smoothly and securely.
Don’t settle for the first quote you receive online—remember that smart shopping and comparing terms can save you tens of thousands of dollars over the lifetime of your loan.
Ready to unlock your earned military home loan benefits with a local specialist who puts your financial goals first? Visit VA Home Mortgage today to connect directly with our team, pull your COE, and take the first confident step toward owning your home!


