
VA Streamline Refinance Rates: A Fast Answer for VA Homeowners
VA streamline refinance rates can be lower than the rate on your current VA mortgage, but the rate you receive depends on your credit profile, loan term, lender fees, discount points, and the day you lock your loan.
As of August 2026, the national average for a 30-year VA refinance is about 6.40%, while some advertised 30-year VA refinance offers are as low as 5.375%. Those are not guaranteed rates. A low advertised rate may require strong credit, points paid at closing, and other lender-specific conditions.
A VA streamline refinance, also called an Interest Rate Reduction Refinance Loan (IRRRL), replaces an existing VA-backed mortgage. It is designed to lower your rate or payment, or move you from an adjustable-rate mortgage to a fixed rate with steadier payments. In many cases, it requires less paperwork than a full refinance and may not require an appraisal.
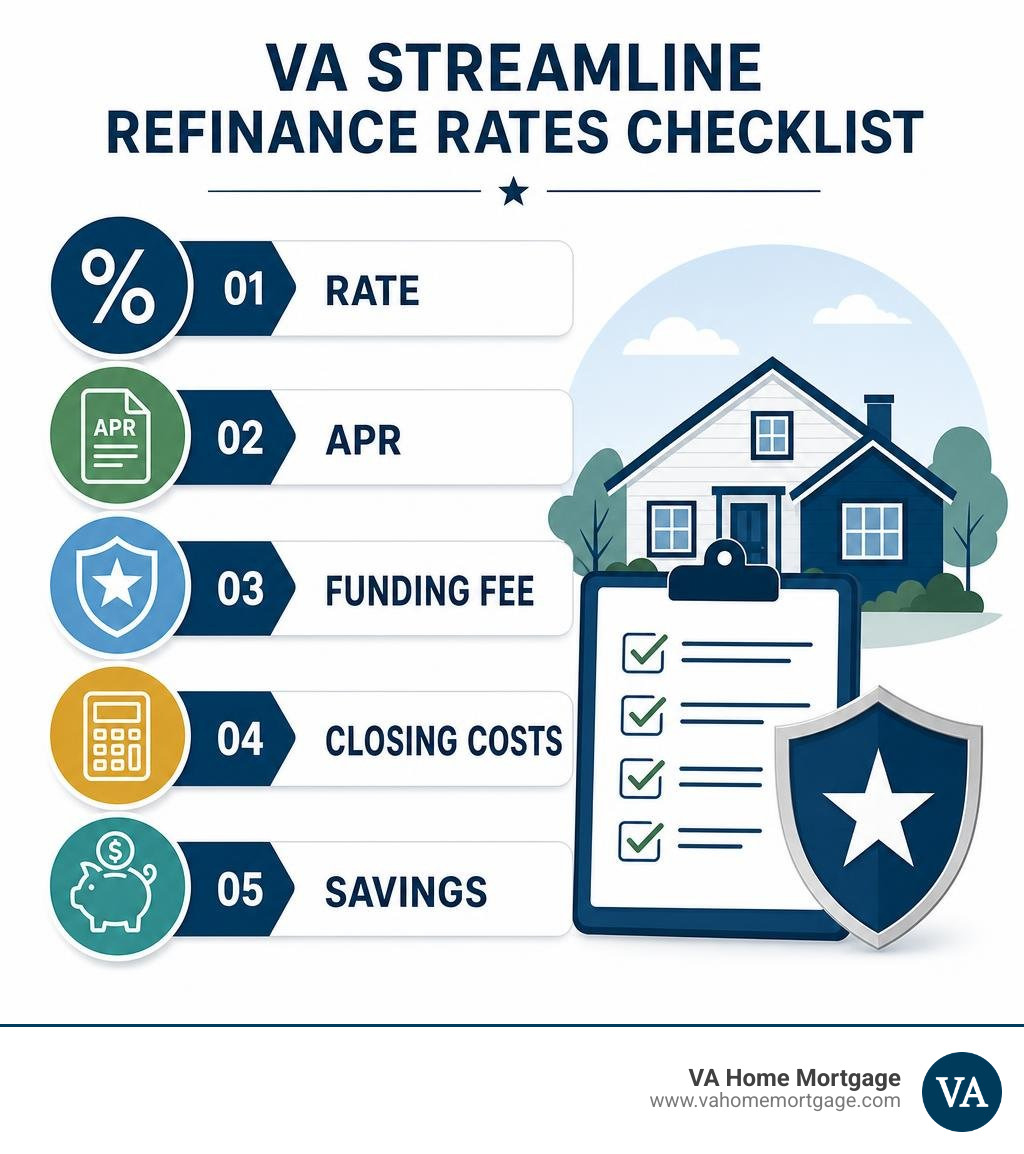
Before refinancing, focus on the full cost, not just the headline rate:
- Compare the interest rate and APR from several VA-approved lenders.
- Include the 0.50% VA funding fee if you are not exempt.
- Check whether closing costs are financed into the loan or covered with lender credits.
- Confirm your monthly savings outweigh the costs within a reasonable break-even period.
I am Dale Gremillion, a Senior Loan Officer and Producing Branch Manager with more than 25 years in residential lending, including VA purchase, refinance, and cash-out loans. I help borrowers evaluate VA streamline refinance rates and closing costs so they can pursue a simpler refinance with clear expectations.
What Is a VA IRRRL and How Do You Qualify?
An Interest Rate Reduction Refinance Loan (IRRRL), commonly known as a VA streamline refinance, is a special benefit created specifically for military members, veterans, and surviving spouses who already have an active VA loan. Unlike standard home loans where you have to jump through endless financial hoops, the U.S. Department of Veterans Affairs designed the IRRRL to be as low-stress as possible.
The primary goal of the streamline program is to help you take advantage of lower VA streamline refinance rates or move out of an unpredictable adjustable-rate mortgage (ARM) into a rock-solid fixed-rate loan. Because you have already proven your eligibility when securing your original VA mortgage, the federal government relaxes many standard loan requirements.
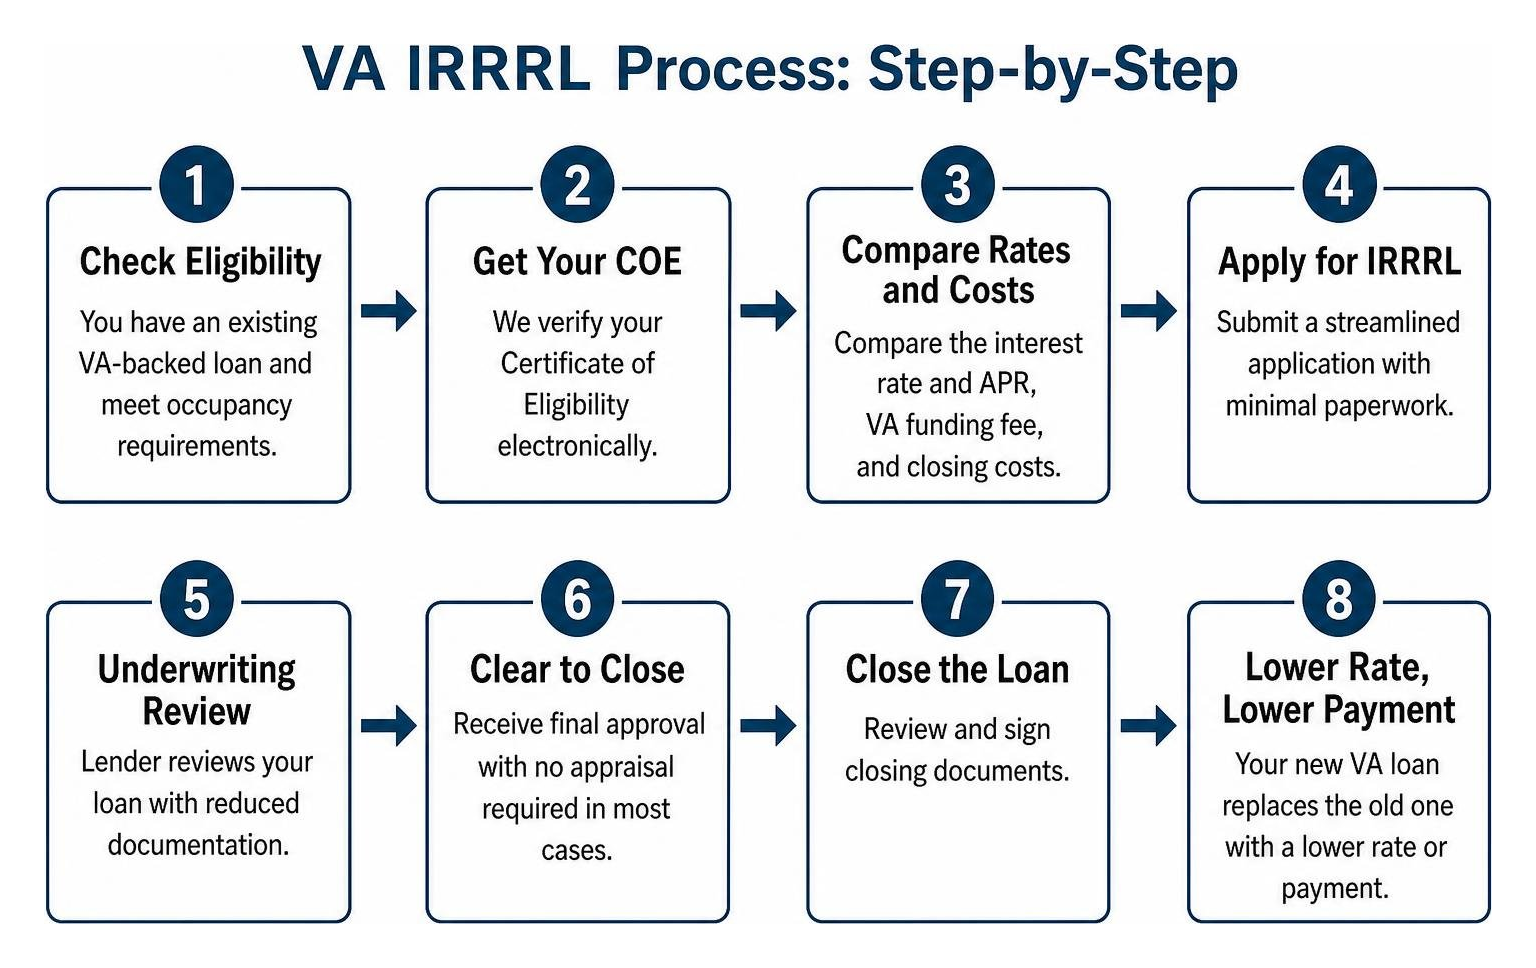
To qualify for an IRRRL, you must meet a few core criteria:
- Existing VA Loan: You must be refinancing a home mortgage that is currently backed by the VA. You cannot use an IRRRL to convert an FHA, USDA, or conventional mortgage into a VA loan.
- Certificate of Eligibility (COE): Your original entitlement must be verified. We can pull your COE electronically in a matter of seconds.
- Occupancy Rules: Unlike a original VA purchase loan where you must occupy the home as your primary residence immediately, an IRRRL only requires you to certify that you currently live in or previously lived in the home. This makes the streamline program an incredible tool if you have been reassigned, relocated, or converted your former home into a rental property.
To dive deeper into standard guidelines and eligibility checks, check out The Complete Guide to VA Refinance Eligibility.
Qualification Rules: Credit, Seasoning, and Occupancy
While the VA itself does not establish a strict minimum credit score or require full income re-verification for an IRRRL, private mortgage lenders enforce their own internal standards (known as lender overlays).
Here is how the main qualification rules break down in practice:
- Seasoning Requirement (The 210-Day Rule): You cannot refinance on a whim right after closing your initial mortgage. To satisfy official seasoning rules, you must have made at least six consecutive monthly payments on your current loan, and at least 210 days must have passed since the due date of your first monthly payment.
- Payment History: Clean payment records are essential. Most lenders require that you have zero 30-day late payments over the past 12 months on your existing mortgage.
- Credit Score Expectations: Although the VA doesn’t impose a score baseline, most direct lenders look for credit scores around 620 or higher to secure competitive VA streamline refinance rates. Borrowers with top-tier scores (720 to 850) naturally unlock the sharpest terms.
- Occupancy Certification: You simply sign a form stating you lived in the residence at some point during your ownership.
Required Documentation and Streamlined Timeline
Because an appraisal, extensive pay stubs, and tax returns are generally bypassed on a standard IRRRL, the paperwork pile drops significantly.
We typically only need:
- A copy of your current mortgage statement.
- Proof of your homeowner’s insurance policy.
- Your driver’s license or government ID.
- Your Certificate of Eligibility (which we retrieve for you).
Thanks to in-house underwriting and direct VA authority, standard IRRRL processing moves rapidly. While traditional refinances can stretch out anywhere from 30 to 45 days, a VA streamline refinance typically wraps up in just 15 to 21 days from start to finish.
Understanding VA Streamline Refinance Rates and Market Trends
Mortgage markets shift constantly based on broader macroeconomic signals, Federal Reserve monetary policy, and inflation data. Tracking current benchmark averages gives you a baseline for evaluating whether a market dip presents a genuine savings opportunity.
As of August 2026, mortgage rates reflect steady conditions. According to a Current refi mortgage rates report for Aug. 13, 2026 | Fortune, the national average 30-year fixed refinance rate sat at 6.756%, down slightly from 6.830% recorded earlier in the month. However, because government-backed VA loans carry a federal guarantee that lowers lender risk, actual VA streamline refinance rates frequently run 0.125% to 0.25% lower than conventional refinance options.
To compare current live rate benchmarks across products, check Compare VA refinance rates today | Bankrate.
Factors That Influence VA Streamline Refinance Rates
No two borrowers receive the exact same rate quote on the exact same day. Several key levers directly impact the interest rate you are offered:
- Credit Score Tiers: Across the industry, 30-year VA fixed refinance rates for borrowers in the 720-850 credit tier averaged around 6.73% at credit unions, 6.83% at online lenders, and 7.13% at traditional retail banks as of August 2026.
- Lender Structure: Institutional overhead matters. Direct mortgage lenders with direct VA underwriting authority often provide more aggressive rate structures compared to brick-and-mortar retail banks.
- State Variations: Local economic climates and property tax structures influence pricing. For instance, recent market reports highlight average 30-year VA refinance rates ranging from 5.66% in Hawaii to 6.56% in states like Alabama and Illinois for tier-one credit profiles.
- Discount Points: You can choose to pay discount points upfront (where 1 point equals 1% of your loan amount) to permanently buy down your interest rate.
How to Lock in the Best VA Streamline Refinance Rates
Shopping for a streamline refinance isn’t just about chasing headline numbers; it’s about evaluating the Annual Percentage Rate (APR). The APR reflects your actual annual cost of borrowing, incorporating upfront fees, points, and processing expenses alongside the baseline note rate.
Unfocused shopping costs real money. Industry statistics reveal that homeowners who fail to compare multiple quotes overpay an average of $2,462 every single year on their mortgage!
Here is how rate expectations generally compare across lender categories for a borrower with strong credit:
| Lender Category | Average Note Rate Range | Key Advantage | Typical Processing Speed |
|---|---|---|---|
| VA Direct Lenders | 5.375% – 6.25% | In-house decisions, fast execution, direct VA focus | 15 – 21 Days |
| Credit Unions | 5.875% – 6.73% | Competitive member pricing | 25 – 35 Days |
| Online Brokers | 6.25% – 6.83% | Convenient digital platforms | 20 – 30 Days |
| Traditional Retail Banks | 6.75% – 7.13% | Existing banking relationships | 30 – 45 Days |
When you find a favorable window, securing a formal rate lock protects your pricing from market spikes while your paperwork moves through underwriting.
VA Streamline vs. VA Cash-Out Refinancing
Choosing the right loan structure depends entirely on your financial goals. While an IRRRL focuses strictly on lowering your payment or fixing your rate, a VA Cash-Out Refinance allows you to convert home equity into cash for debt consolidation, home repairs, or major purchases.
For a full breakdown of all refinancing options, review The Ultimate Guide to VA Home Mortgage Refinancing.
Here is how the two programs contrast:
- VA IRRRL (Streamline): Replaces an existing VA loan only. Requires no appraisal in most cases, limited documentation, and features a low 0.50% VA funding fee. You cannot take cash out at closing (other than minor reimbursement for overpaid escrow balances up to $500).
- VA Cash-Out Refinance: Can replace any loan type (VA, FHA, or conventional). Requires a full home appraisal, standard income verification, credit underwriting, and carries a higher VA funding fee (2.15% for first-time use or 3.30% for subsequent use).
Weighing Pros, Cons, and Net Tangible Benefit
To protect military families from aggressive churn, the Department of Veterans Affairs enforces a strict Net Tangible Benefit (NTB) test on all IRRRL refinances. We must mathematically prove that the new loan provides a genuine financial advantage.
Specifically, the rules state:
- If you are moving from a fixed rate to another fixed rate, the new interest rate must be at least 0.50% lower than your existing rate.
- If you are moving from an adjustable-rate mortgage (ARM) to a fixed rate, your new rate cannot exceed your current rate, giving you long-term stability without a payment penalty.
- The break-even period for all refinancing fees cannot exceed 36 months.
If you need to access your home equity rather than just reduce your monthly payment, explore Get Maximum Equity with a 100 Percent VA Cash Out Refinance.
Funding Fees, Closing Costs, and Break-Even Analysis
Every VA streamline refinance involves closing costs, but the program is structured so you rarely have to pay out-of-pocket cash at the closing table.
The centerpiece expense is the mandatory VA Funding Fee, set at 0.50% of your new total loan balance for an IRRRL. On a $300,000 refinance, this fee equals $1,500.
Additional closing expenses include title insurance, escrow setup, recording fees, and lender origination fees. Fortunately, the VA allows you to roll all allowable closing costs and the funding fee directly into your new loan principal. Alternatively, you can accept a slightly higher interest rate in exchange for lender credits that cover your closing expenses.
Calculating your break-even point is easy:
- Add up total closing costs and funding fees: e.g., $3,600.
- Calculate your net monthly payment savings: e.g., $150 per month.
- Divide total costs by monthly savings: $3,600 / $150 = 24 months.
In this example, once you remain in your home for 24 months, your refinance has paid for itself completely, and every month after represents pure savings.
Frequently Asked Questions About VA Refinancing
How long does a VA IRRRL process take from application to closing?
Because an IRRRL bypasses home appraisals, full income verification, and extensive asset auditing, processing speeds are exceptionally swift. At Capital Home Mortgage, our direct VA authority and in-house underwriting allow us to complete most streamline refinances within 15 to 21 days from application submission to final closing.
Do I need a home appraisal for a VA streamline refinance?
No! The VA does not require a home appraisal or property valuation for a standard IRRRL. This means even if home values in your neighborhood have softened slightly, your loan eligibility remains intact because your property’s current home equity value is not re-assessed.
Who is exempt from paying the VA funding fee?
You are completely exempt from paying the 0.50% VA funding fee if you meet any of the following conditions:
- You receive VA compensation for a service-connected disability.
- You are entitled to receive VA disability compensation but receive active-duty retirement pay instead.
- You are a surviving spouse of a veteran who died in service or from a service-connected disability.
- You are an active-duty service member who has been awarded the Purple Heart.
Exemption status is officially verified on your Certificate of Eligibility prior to loan closing.
Conclusion
Refinancing your home loan shouldn’t feel like a full-time job. With VA streamline refinance rates offering an efficient pathway to monthly mortgage savings, an IRRRL stands out as one of the most rewarding benefits earned through your military service.
By capitalizing on fast processing, zero out-of-pocket options, no appraisal requirements, and minimal documentation, you can lower your monthly obligation and keep more hard-earned money in your pocket every month.
At Capital Home Mortgage, we take immense pride in serving those who served our nation. As a direct VA mortgage lender with in-house underwriting, we offer streamline refinancing, cash-out loans, and purchase options with direct authority, fast processing, and no PMI.
Ready to lock in your savings? Learn How to Contact a Local VA Home Loan Representative or visit VA Home Mortgage today to get your custom rate quote!


