
Understanding VA Loan Eligibility, Loan Types, and Key Benefits
To start your VA home loan application, gather your military service verification (such as your DD-214 or Statement of Service) alongside recent tax and income records, retrieve your Certificate of Eligibility (COE), and submit your application to a VA-approved lender to secure pre-approval. Following this structured preparation ensures a fast, straightforward mortgage process without unnecessary underwriting delays.
Established by the Servicemen’s Readjustment Act of 1944, the VA loan program has empowered over 24 million Veterans, active-duty personnel, and surviving spouses to achieve affordable homeownership. Because the Department of Veterans Affairs guarantees a substantial portion of each loan against default, approved direct lenders like us can offer terms that conventional loan products simply cannot match.
The core advantages of the program include:
- 0% Down Payment: Eligible borrowers can finance 100% of a home’s reasonable value without parting with hard-earned savings.
- No Private Mortgage Insurance (PMI): Conventional loans typically require expensive monthly mortgage insurance when putting down less than 20%. VA loans completely eliminate monthly PMI or mortgage insurance premiums (MIP), saving you hundreds of dollars every month.
- Competitive Interest Rates: Backed by the federal government, VA interest rates consistently rank among the most favorable on the market.
- Lifetime Benefit: Your VA loan entitlement is not a one-and-done opportunity; you can reuse your benefit throughout your lifetime.
- No Maximum Loan Limits for Full Entitlement: Under the Blue Water Navy Vietnam Veterans Act, statutory loan limits have been eliminated for qualified buyers holding full entitlement.
By unlocking your military housing benefits with home loans VA, you can build generational wealth while maintaining cash reserves for personal investments and daily living expenses.
| VA Loan Option | Primary Purpose | Down Payment Requirement | Funding Fee Structure | New COE Required? |
|---|---|---|---|---|
| VA Purchase Loan | Buy a single-family home, approved condo, or 1-4 unit multi-family property | 0% | 2.3% first-time use (0% down); 3.6% subsequent use | Yes |
| Interest Rate Reduction Refinance Loan (IRRRL) | Refinance an existing VA loan to lower the interest rate or adjust term lengths | 0% (costs rolled into loan) | 0.50% of the loan balance | No (prior use verification suffices) |
| VA Cash-Out Refinance | Extract equity for debt consolidation, home improvements, or cash needs | 0% equity minimum (up to 100% loan-to-value) | 2.3% first-time use; 3.6% subsequent use | Yes |
| Native American Direct Loan (NADL) | Direct financing to buy, build, or improve homes on Federal Trust land | 0% | 1.25% of the loan amount | Yes |
Service Requirements Across Military Branches and Surviving Spouses
Qualifying for a VA home loan begins with meeting statutory service benchmarks established by Congress. The VA looks closely at your total length of service and your character of service. In general, an applicant must have received an honorable discharge; dishonorable conditions or bad conduct discharges disqualify an applicant from the program.
The minimum service requirements vary based on the era and military component:
- Active Duty: 90 continuous days of active service during wartime, or 181 continuous days during peacetime.
- Gulf War Era (August 2, 1990, to present): 24 continuous months of active-duty service, or the full period (at least 90 days) for which you were called to active duty.
- National Guard: At least 90 days of non-training active-duty service, including at least 30 consecutive days under Title 32 orders (specifically sections 316, 502, 503, 504, or 505), or 6 creditable years in the Selected Reserve.
- Reserves: 6 creditable years of service in the Selected Reserve with an honorable discharge, placement on the retired list, or continued service in the Standby Reserve.
- Surviving Spouses: An unremarried surviving spouse of a Veteran who died on active duty, died as a result of a service-connected disability, or was rated totally disabled and eligible for Dependency and Indemnity Compensation (DIC) can qualify for full VA home loan benefits.
For comprehensive guidelines detailing wartime brackets and eligibility nuances, refer to the official VA Home Loan Guaranty Buyer’s Guide.
Purchase, Refinance, and Native American Direct Loan Options
Whether you are stepping into homeownership for the first time or managing an existing portfolio, the VA loan suite covers a diverse range of financing options:
- Standard Purchase Loans: Designed for buying primary residences, including detached single-family houses, approved condominiums, manufactured homes attached to permanent foundations, and multi-unit buildings (up to 4 units, provided you occupy one).
- Interest Rate Reduction Refinance Loans (IRRRL): Also known as the VA Streamline Refinance, this program lets you lower your monthly payment with minimal underwriting, no home appraisal, and no income verification in most cases.
- VA Cash-Out Refinance: Homeowners looking to pay off high-interest debt or fund major renovations can review The Ultimate Guide to a 100% Cash Out Refi to access up to 100% of their home’s appraised equity.
- Native American Direct Loans (NADL): Unlike guaranteed loans originated by private lenders, the VA acts as the direct mortgage lender for eligible Native American Veterans purchasing or renovating property on covered Federal Trust land.
- Specially Adapted Housing (SAH) and Special Housing Adaptation (SHA) Grants: Grant programs (using VA Form 26-4555) that assist Veterans with specific service-connected disabilities in purchasing, constructing, or modifying homes to achieve independent living.
To fund program operations, the VA charges a one-time VA funding fee, which can be financed directly into the loan amount. For a first-time purchase with 0% down, the fee is 2.3%, rising to 3.6% for subsequent uses. Making a down payment of 5% or more reduces this fee tier to 1.5% (or 1.25% with 10% down).
Certain borrowers are completely exempt from the funding fee, including:
- Veterans receiving VA compensation for a service-connected disability.
- Veterans entitled to receive disability compensation who are receiving retirement or active-duty pay instead.
- Surviving spouses receiving DIC benefits.
- Active-duty service members who provide evidence of receiving the Purple Heart prior to or at loan closing.
The 7-Day Roadmap to Master Your VA Home Loan Application
Starting your mortgage application does not have to feel overwhelming. By breaking down the tasks across a structured seven-day window, you can move efficiently from gathering records to securing a solid pre-approval.
Days 1 to 3: Gathering Documents for Your VA Home Loan Application
The foundation of a smooth mortgage process is thorough documentation. Gathering your military records, income statements, and asset verifications early prevents underwriting delays down the line.
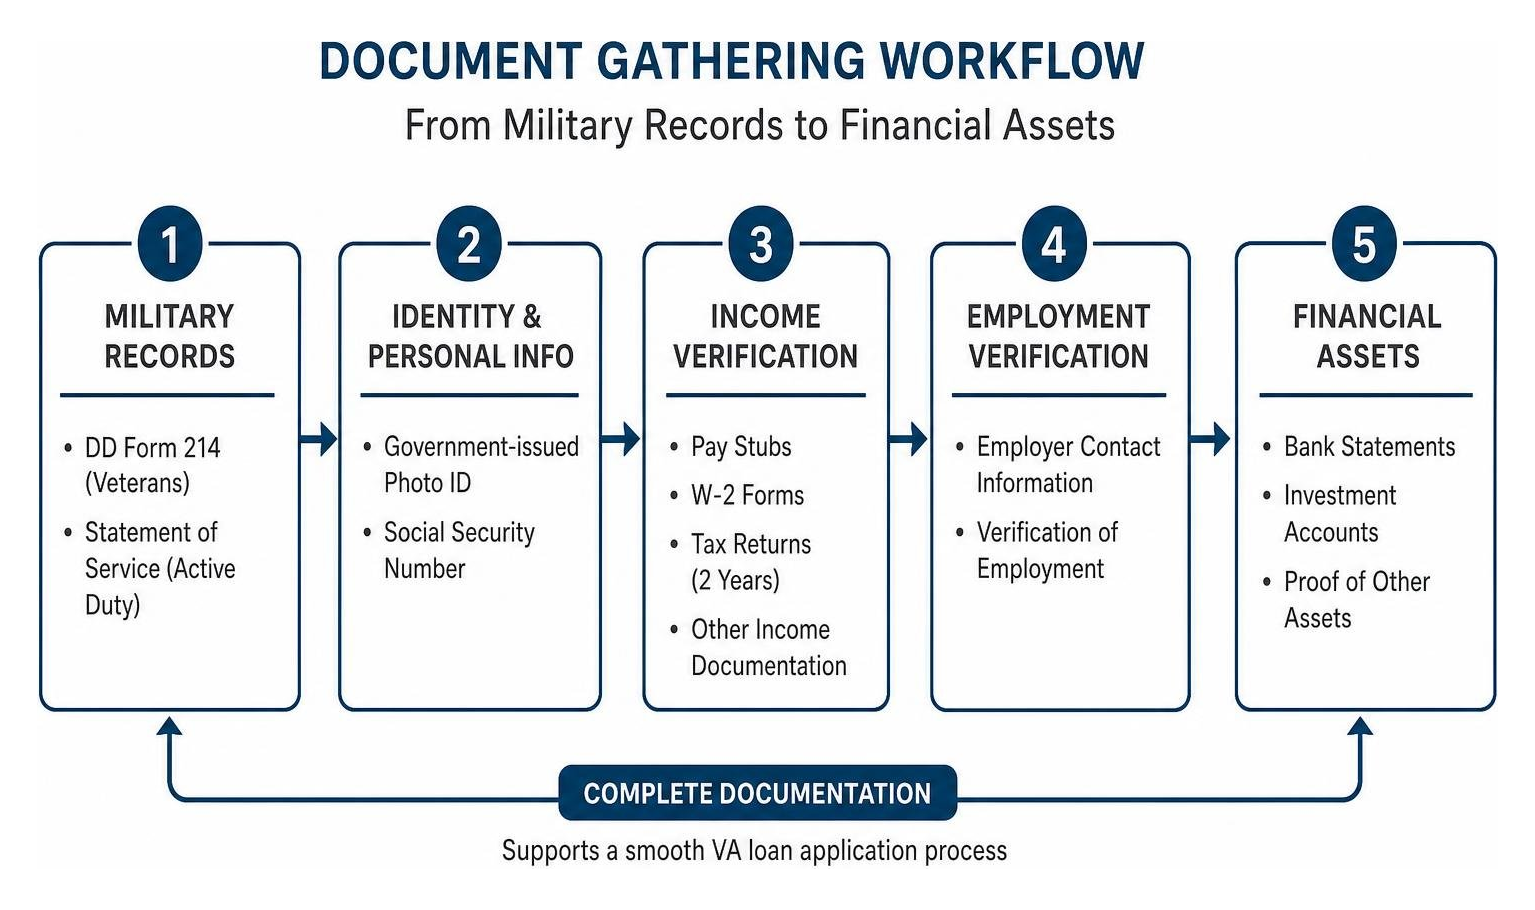
Prepare the following records:
- Military Service Verification:
- Veterans: DD Form 214 (Certificate of Release or Discharge from Active Duty), Member 4 copy, showing Item 24 (Character of Service) and Item 28 (Narrative Reason for Separation).
- Active Duty Personnel: A Statement of Service signed by your commander, adjutant, or personnel officer. It must include your full legal name, Social Security number, date of birth, date entered active duty, duration of any lost time, and command name.
- National Guard Members: NGB Form 22 (Report of Separation and Record of Service) or NGB Form 23 (Retirement Points Accounting Statement).
- Reservists: Latest annual retirement points statement and documentation of honorable service.
- Surviving Spouses: VA Form 26-1817, the Veteran’s DD-214 (if available), marriage certificate, and official death certificate or casualty report.
- Income and Tax Records:
- W-2 forms covering the past two consecutive tax years.
- Recent 30 consecutive days of pay stubs (or Leave and Earnings Statements for active service members).
- Two years of complete federal personal tax returns (1040s) with all schedules if self-employed, receiving commission, or using rental income.
- Two years of corporate or partnership tax returns (1120, 1120-S, 1065) with profit and loss statements for business owners.
- Asset and Financial Disclosures:
- Checking and savings statements for the last two full banking cycles (all pages included).
- Retirement, 401(k), IRA, and investment account statements.
- Divorce decrees, child support agreements, or bankruptcy discharge paperwork (if applicable within the last 7 years). If you are purchasing direct government-acquired inventory, make sure to review the Credit Statement of Prospective Purchaser guidelines.
Days 4 to 5: Obtaining Your COE and Evaluating Lender Requirements
Once your initial records are organized, turn your attention to your Certificate of Eligibility and review how lenders evaluate your credit profile.
You can request your COE through three primary pathways:
- Through a VA-Approved Lender (Fastest): Direct lenders connected to the VA’s internet-based Web LGY portal can typically retrieve and confirm your COE electronically within minutes.
- Online via VA.gov: You can submit your military documentation directly into the VA’s online portal and monitor the processing status.
- By Mail (Slowest): Complete and mail VA Form 26-1880 alongside physical copies of your military service records to your VA Regional Loan Center, which can take several weeks.
To review official entitlement policies, check the Certificate of Eligibility – VA Home Loans guidelines. If you run into complex service history questions, learning how to contact a local VA home loan representative can help you get direct answers from regional loan centers.
While the VA determines your eligibility via the COE, private mortgage lenders establish qualification through underwriting standards known as lender overlays:
- Credit Scores: The VA does not mandate a universal minimum credit score. However, most lenders look for a benchmark score of 620 to ensure predictable repayment history.
- Debt-to-Income (DTI) Ratio: While a 41% DTI ratio is the standard guideline, automated underwriting systems can approve higher DTIs when compensating factors exist, such as substantial cash reserves or excellent residual income.
- Residual Income Standards: The VA requires borrowers to retain a set amount of discretionary cash each month after covering taxes, mortgage payments, and revolving debts. This regional benchmark protects military families from becoming house-poor.
Days 6 to 7: Pre-Approval and Submitting the Official VA Home Loan Application
With your COE in hand and financial records assembled, you are ready to secure a pre-approval and formally submit your mortgage application.
During these final days of your 7-day sprint:
- Submit the Uniform Residential Loan Application (URLA / Fannie Mae Form 1003): This standard document outlines your employment, income, real estate assets, and monthly liabilities.
- Sign the HUD/VA Addendum: Federal regulations require every borrower to sign the HUD/VA Addendum to Uniform Residential Loan Application (VA Form 26-1802a). This addendum certifies your intent to occupy the property as your primary residence within 60 days of closing (or verifies spouse occupancy if you are currently deployed).
- Review Your Loan Estimate (LE): Lenders must deliver a detailed Loan Estimate within three business days of receiving your completed application. Use this document to evaluate origination charges, discount points, third-party vendor fees, and escrow deposits.
- Leverage the 45-Day Credit Window: Credit bureaus treat all mortgage-related credit inquiries made within a 45-day window as a single inquiry, allowing you to shop for the most competitive terms without dinging your credit scores.
Take time during this stage to compare loan offers by understanding current 30-year VA mortgage rates today so you can lock in favorable financing.
From Underwriting to Closing: Appraisals, Inspections, and Clear to Close
After submitting your application and executing a purchase agreement, your loan enters the processing and underwriting pipeline. Knowing the difference between required property appraisals and independent home inspections will keep your transaction moving smoothly toward closing day.
VA Appraisal vs Independent Home Inspection
Many buyers mistake a VA appraisal for a home inspection, but they serve two very different purposes during the purchase process.
The differences include:
- The VA Appraisal: Conducted by an independent VA-assigned appraiser, this assessment establishes the property’s fair market value and verifies compliance with the VA’s Minimum Property Requirements (MPRs). MPRs ensure the home is safe, sanitary, and structurally sound (checking for functioning heating systems, clean drinking water, adequate roofing, and absence of wood-destroying insects). The appraiser issues a Notice of Value (NOV).
- The Independent Home Inspection: An optional but essential evaluation hired directly by you. An inspector checks the property from foundation to rafters, identifying deferred maintenance, plumbing leaks, electrical hazards, and HVAC lifespan issues.
Always ensure your purchase contract includes the mandatory VA Escape Clause. This federal safeguard states that you cannot be forced to complete the purchase or forfeit your earnest money deposit if the property’s appraised value comes in lower than the agreed purchase price. If an appraisal comes in low, your lender can submit a Reconsideration of Value (ROV) with comparable sales, or you can renegotiate the purchase price with the seller.
For more details on navigating these milestones, refer to the official VA home buying process guide.
Navigating Loan Disclosures and Closing Timelines
As underwriting wraps up and your loan receives “Clear to Close” status, you will transition through final settlement procedures.
- Review the Closing Disclosure (CD): Under federal law (the TRID 3-day rule), your lender must provide your final Closing Disclosure at least three business days prior to loan consummation. Compare every line item against your initial Loan Estimate to verify interest rates, monthly payments, and total closing costs.
- Manage Allowable Closing Costs and Seller Concessions: The VA limits the types of fees lenders can charge borrowers. Additionally, sellers can contribute up to 4% of the total purchase price in seller concessions, which can cover prepaid taxes, insurance, discount points, or payoff of buyer credit card balances at closing.
- Secure Title Insurance: Your lender will require a Lender’s Title Insurance Policy to protect against liens on the property. We strongly recommend purchasing an Owner’s Title Insurance Policy as well to safeguard your personal equity against unrecorded title defects or historical claims.
- Final Signing and Fund Disbursement: You will attend closing at a title company, escrow office, or attorney’s office, sign your final promissory note and mortgage deed of trust, provide any required closing funds via certified cashier’s check or wire transfer, and receive the keys to your new home.
To understand how each phase fits into the overall calendar, read everything to expect from your VA loan closing timeline.
Frequently Asked Questions About the VA Home Loan Process
What assistance is available if a borrower faces financial hardship or foreclosure?
If you experience unexpected financial hardship, military deployment challenges, or income loss, the VA provides extensive loan retention assistance. You can contact a dedicated VA loan technician directly at 877-827-3702 to explore foreclosure avoidance options.
Technicians can work with your loan servicer to establish loss mitigation solutions, such as:
- Repayment Plans: Spreading past-due balances across regular monthly payments over an agreed timeline.
- Forbearance Agreements: Temporarily pausing or reducing monthly mortgage payments while you regain financial footing.
- Loan Modifications: Capitalizing past-due amounts into the principal balance, extending the loan term, or adjusting interest rates to establish an affordable monthly obligation.
How can a borrower restore their full VA loan entitlement after selling a home?
Because your VA home loan entitlement is a lifetime benefit, you can have it fully restored upon selling your property and paying off the existing VA loan in full.
To restore your entitlement:
- Ensure the previous VA-backed mortgage has been completely satisfied through the sale of the home or an approved refinancing mechanism.
- Submit VA Form 26-1880 to the VA along with proof of loan payoff (such as a recorded release of mortgage or final settlement statement).
- The VA will issue an updated Certificate of Eligibility showing your full entitlement balance restored.
The VA also allows a one-time restoration of entitlement if you have paid off a VA loan in full but still retain ownership of the property (for instance, converting it into a rental residence). For a closer look at refinancing rules and entitlement recovery, see The Complete Guide to VA Refinance Eligibility.
Does the Department of Veterans Affairs enforce a minimum credit score?
No. The Department of Veterans Affairs does not set a statutory minimum credit score benchmark. Instead, the VA instructs underwriters to review the borrower’s overall credit profile, income stability, and past 12 months of clean payment history.
However, private mortgage lenders establish their own internal underwriting benchmarks (known as lender overlays). While most institutions look for a baseline credit score of 620, direct lenders with in-house underwriting authority can often evaluate lower credit profiles by looking at compensating factors, such as reliable residual income, long-term employment stability, and cash reserves.
Conclusion
The VA loan benefit remains one of the most powerful financial tools available to U.S. service members, Veterans, and surviving spouses. With zero down payment requirements, no monthly mortgage insurance, competitive interest rates, and capped closing fees, this program offers a clear, reliable pathway to long-term homeownership.
By executing the 7-day roadmap outlined in this guide—gathering your service and income records, retrieving your Certificate of Eligibility, comparing loan options, and securing a solid pre-approval—you can move forward into the housing market with confidence.
At Capital Home Mortgage, our dedicated direct lending team specializes in VA purchase financing, IRRRL streamline refinances, and 100% cash-out loans. With direct VA authority and experienced in-house underwriting, we help you navigate every milestone smoothly from initial application to closing day. Connect with VA Home Mortgage to begin your military home financing journey today.


