
What Does a Dedicated VA Loan Officer Do for Veterans?
To find a qualified VA loan officer, you must verify three critical factors: confirm the originator has VA direct endorsement authority for in-house underwriting, verify that military lending represents a substantial portion of their loan volume, and check that they operate with minimal lender overlays. Working with top VA mortgage lenders ensures you receive full military benefits, including zero down payment and no monthly private mortgage insurance (PMI). While the U.S. Department of Veterans Affairs provides a partial guaranty on every loan, private lenders originate, underwrite, and fund these mortgages.
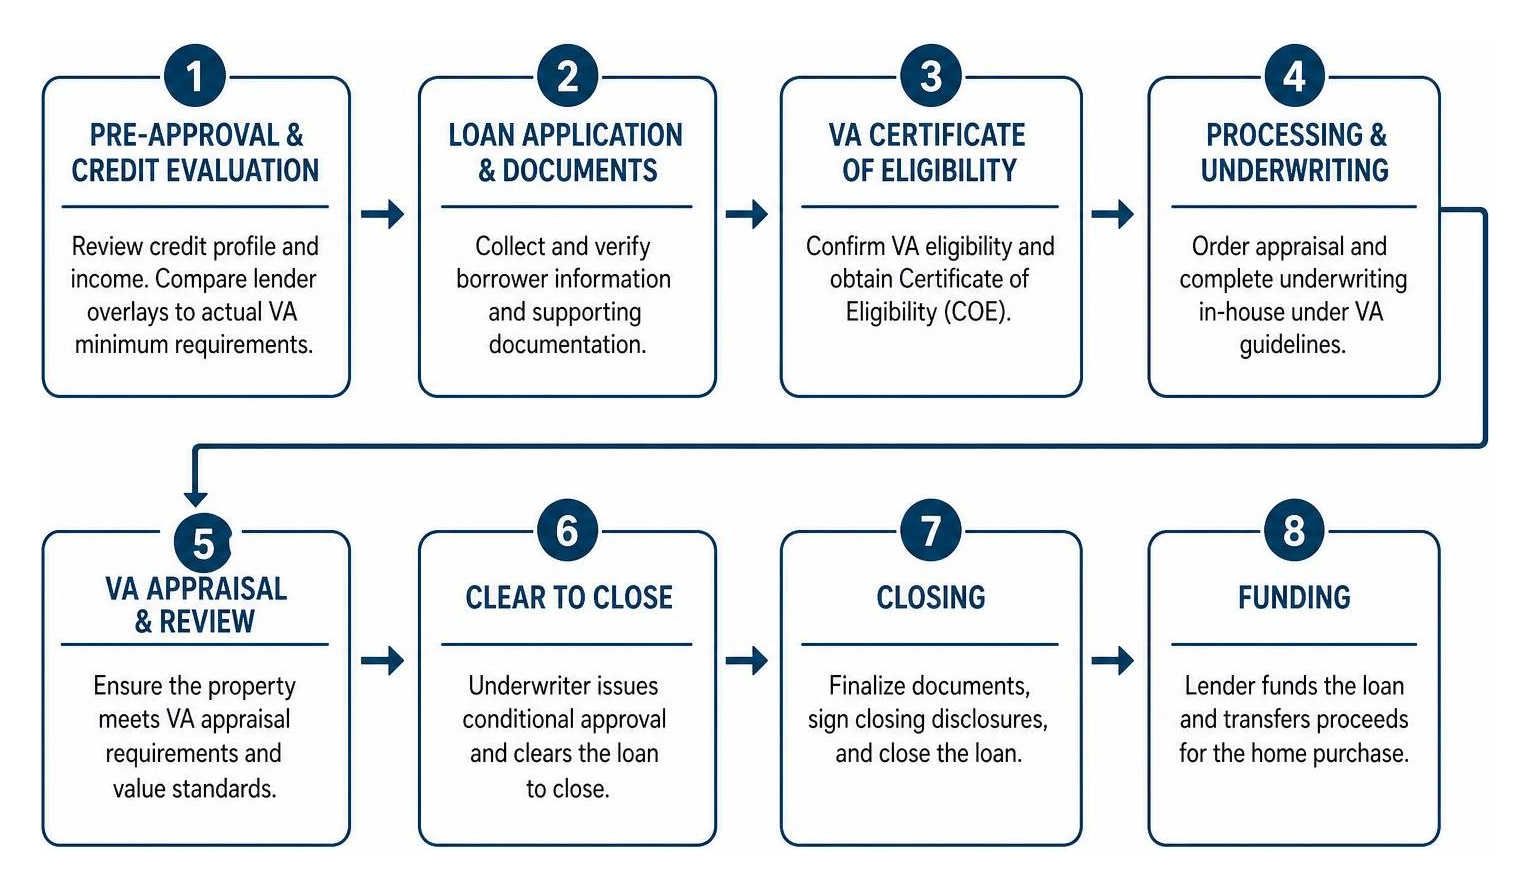
Core Responsibilities of a VA Loan Officer
The day-to-day work of an originator involves balancing borrower advocacy with stringent federal guidelines:
- Initial Pre-Approval & Credit Evaluation: Analyzing credit profiles while reviewing lender overlays versus actual statutory minimums.
- Residual Income Analysis: Calculating region-specific residual income thresholds to confirm you have sufficient cash flow for basic living expenses after paying the mortgage.
- Debt-to-Income (DTI) Structuring: Structuring total monthly debt obligations so the loan file easily meets automated or manual underwriting standards.
- Fee Compliance Monitoring: Enforcing VA non-allowable fee rules to protect you from unapproved lender charges.
- Closing Coordination: Managing communications among real estate agents, appraisers, title companies, and underwriters to keep everything to expect from your VA loan closing timeline completely on track.
Verifying Service Requirements and Obtaining the COE
The foundational step of every transaction is securing your Certificate of Eligibility (COE). A knowledgeable originator connects directly to the VA’s WebLGY portal via AccessVA and ID.me to retrieve your COE in minutes, sparing you weeks of paperwork.
To establish eligibility, an originator reviews your military records against formal service requirements:
- Active Duty: At least 90 continuous days of service during wartime, or 181 continuous days during peacetime.
- National Guard & Reserve: At least 6 years of honorable service, or 90 days of active-duty service that includes at least 30 consecutive days under Title 32 orders (Sections 316, 502, 503, 504, or 505).
- Veterans: Verification via Form DD-214 showing an honorable character of service.
- Surviving Spouses: Form 26-1817 review for un-remarried spouses of service members who died on active duty or from a service-connected disability.
If you have your military paperwork ready, reviewing how to start your VA home loan application in 7 days provides a clear roadmap for pulling records and preparing your financial profile.
Core VA Loan Programs Handled by Specialists
A seasoned specialist tailors loan structures to your specific financial situation while monitoring market movements and understanding current 30-year VA mortgage rates today to lock in optimal financing terms.
Purchase Loans, Cash-Out Refinancing, and IRRRL Transactions
- VA Purchase Loans: Provide 100% financing (zero down payment) on single-family homes, approved condominiums, multi-unit properties (up to 4 units, provided you occupy one), and manufactured homes.
- VA Cash-Out Refinance: Allows homeowners to tap into their home equity up to 100% loan-to-value (LTV) in many cases. This option requires a new appraisal, credit check, and clear proof of a net tangible benefit to consolidate high-interest debt or fund home improvements.
- Interest Rate Reduction Refinance Loan (IRRRL): Often called a VA Streamline Refinance, this program lowers the interest rate on an existing VA loan with reduced documentation. It requires no new appraisal, no fresh COE verification (prior entitlement is verified directly by the lender), and adheres to strict statutory seasoning requirements (at least 210 days from the first payment date and 6 consecutive monthly payments made).
For an exhaustive review of refinance guidelines, explore the complete guide to VA refinance eligibility or consult the ultimate guide to VA home mortgage refinancing for step-by-step transaction structures.
Specialized Financing: NADL and Specially Adapted Housing Grants
Beyond standard purchase and refinance mortgages, specialized housing benefits exist for unique circumstances:
- Native American Direct Loans (NADL): Designed for eligible Native American veterans purchasing, constructing, or improving homes located on Federal Trust Land. Originators assist borrowers in coordinating with the VA, which directly funds these loans if the tribal government has established a formal Memorandum of Understanding (MOU). Contact the direct NADL team at (888) 349-7541 or via
NADL@va.gov. - Specially Adapted Housing (SAH) & Special Housing Adaptation (SHA) Grants: Administered via VA Form 26-4555, these grants help veterans with severe, service-connected disabilities construct, remodel, or adapt residential properties to achieve independent living (e.g., wheelchair ramps, widened doorways, roll-in showers). A dedicated originator can coordinate closing logistics when grant funds are combined with a permanent purchase loan.
Step-by-Step Process to Select the Right VA Specialist
Not all mortgage professionals understand the nuances of the VA home loan program. Choosing an originator with deep military lending experience prevents delays and protects your homebuying earnest money.
| Evaluation Metric | Dedicated VA Mortgage Specialist | General Mortgage Broker |
|---|---|---|
| Underwriting Authority | VA Direct Endorsement (In-House) | Third-Party Wholesale Underwriters |
| COE Resolution Speed | Instant WebLGY / ServiceNow integration | Manual mail-in or third-party delay |
| Credit Score Overlays | Flexible / True VA guidelines (down to 580 or lower) | Strict investor overlays (often 640–680 minimums) |
| Appraisal Defense (Tidewater) | Proactive comparable sales submission | Reactive / Unfamiliar with formal ROV processes |
| Residual Income Expertise | Precise regional table calculations | Often confused with standard DTI limits |
Key Questions to Ask a Potential VA Loan Officer
Before signing a loan application or paying for a credit report, interview your lending professional using these targeted questions:
- What percentage of your total loan volume comes from VA originations? (Look for specialists who focus heavily on military lending.)
- Do you possess VA Direct Authority (in-house delegated underwriting)?
- What are your company’s internal credit score overlays compared to official VA standards?
- How do you handle low property valuations under the VA Tidewater process?
- Can you explain the exact calculation for my local VA residual income requirement?
If you want immediate local support, learning how to contact a local VA home loan representative helps you connect with qualified professionals in your area.
Red Flags to Avoid When Evaluating Lenders
- Mandatory Down Payment Claims: Stating that all VA loans require 3% to 5% down (a sign of internal lender overlays, not VA policy).
- Charging Unallowable Fees: Attempting to charge attorney fees, document preparation fees, or loan application fees directly to the veteran outside the standardized 1% lender origination fee cap.
- Predatory Refinance Solicitations: Mailing deceptive notices promising skipped mortgage payments or teaser rates without presenting the mandatory VA Net Tangible Benefit disclosure.
- Refusing Manual Underwriting: Automatically denying an applicant with a solid credit history simply because automated underwriting systems (AUS) gave a “Refer” recommendation.
Underwriting, Appraisals, and VA Support Infrastructure
VA loans require a property to meet Minimum Property Requirements (MPRs) ensuring the home is safe, structurally sound, and sanitary. Property assignments are managed through WebLGY, which randomly assigns a certified independent VA panel appraiser to the transaction.
Managing VA Appraisals and Reconsiderations of Value
If an appraiser believes the purchase price exceeds market value, they invoke the Tidewater Initiative. This gives the originator and real estate agents 48 hours to supply additional comparable sales before the final Notice of Value (NOV) is issued.
If the final appraisal still comes in below the contract price, an experienced originator initiates a formal Reconsideration of Value (ROV). The originator organizes market data, challenges incorrect appraisal adjustments, and submits an official appeal packet directly to the VA Regional Loan Center (RLC) staff appraisal reviewer.
For condominium purchases, the originator verifies the development’s status on the VA Approved Condominium list or compiles project documents (bylaws, financial reserves, owner-occupancy ratios) to submit a formal condo approval package directly through WebLGY.
VA Administrative Systems, ServiceNow, and Loss Mitigation
When unique policy interpretations, complex service histories, or system corrections arise, originators use the VA ServiceNow Customer Service Management (CSM) portal. Authenticated via AccessVA and ID.me, this platform allows lenders to submit direct support cases to VA Regional Loan Centers for fast administrative resolution.
VA specialists and borrowers can also reach VA Loan Technicians directly:
- Toll-Free Phone Support: (877) 827-3702 (Monday–Friday, 8:00 AM – 6:00 PM EST)
- Veterans Crisis Line: 988 (Press 1)
- Native American Direct Loan Support: (888) 349-7541
Frequently Asked Questions About VA Mortgage Financing
How does a VA loan officer assist borrowers facing financial hardship or foreclosure?
If you encounter financial difficulties, a specialized originator or servicer can connect you with dedicated VA loan technicians. VA technicians offer free foreclosure avoidance counseling and explore loss mitigation options, such as:
- Repayment Plans: Spreading past-due balances over a scheduled period.
- Special Forbearance: Pausing or reducing payments temporarily during economic shocks or natural disasters.
- Loan Modification: Capitalizing delinquent amounts back into the principal balance while extending the loan term to reduce monthly payments.
- VA Servicing Purchase (VASP): Programs where the VA purchases the mortgage directly from the private servicer to adjust loan terms to an affordable fixed rate.
What is the fastest way for a loan officer to resolve complex VA eligibility questions?
The fastest channel is submitting an inquiry through the VA ServiceNow CSM portal using AccessVA credentials. This routes the issue directly to the assigned VA Regional Loan Center (RLC) eligibility team. For immediate, high-priority issues, originators call the dedicated national lender support line at (877) 827-3702 to speak with an RLC specialist.
Can a veteran use the VA loan benefit more than once with a loan officer?
Yes. The VA home loan is a lifetime, reusable benefit. Once a previous VA loan is paid in full and the home is sold, you can restore your full entitlement using VA Form 26-1880.
Additionally, you can purchase a new primary residence using “bonus” or second-tier entitlement without selling your previous home, provided you have sufficient remaining entitlement to satisfy statutory guaranty minimums.
Conclusion
Maximizing your military housing benefits requires working with a lending professional who understands the specific nuances of the VA guaranty program. From pulling complex service records to defending appraisals and waiving monthly mortgage insurance, the right financing partner makes all the difference.
At Capital Home Mortgage, we operate with VA direct authority and in-house underwriting, providing military families with clear communication, competitive rates, and fast closing timelines.
Reach out to our dedicated VA Home Mortgage Team today to verify your eligibility, calculate your purchasing power, and begin your path to homeownership.


