
Streamline a 30-Year VA Loan With an IRRRL
A 30 year VA Interest Rate Reduction Refinance Loan (IRRRL) lets an eligible Veteran, service member, or surviving spouse replace an existing VA mortgage with a new VA loan. It can lower your interest rate, move you from an adjustable-rate mortgage to a fixed rate, or improve payment stability – often without a new appraisal or a full credit underwriting package.
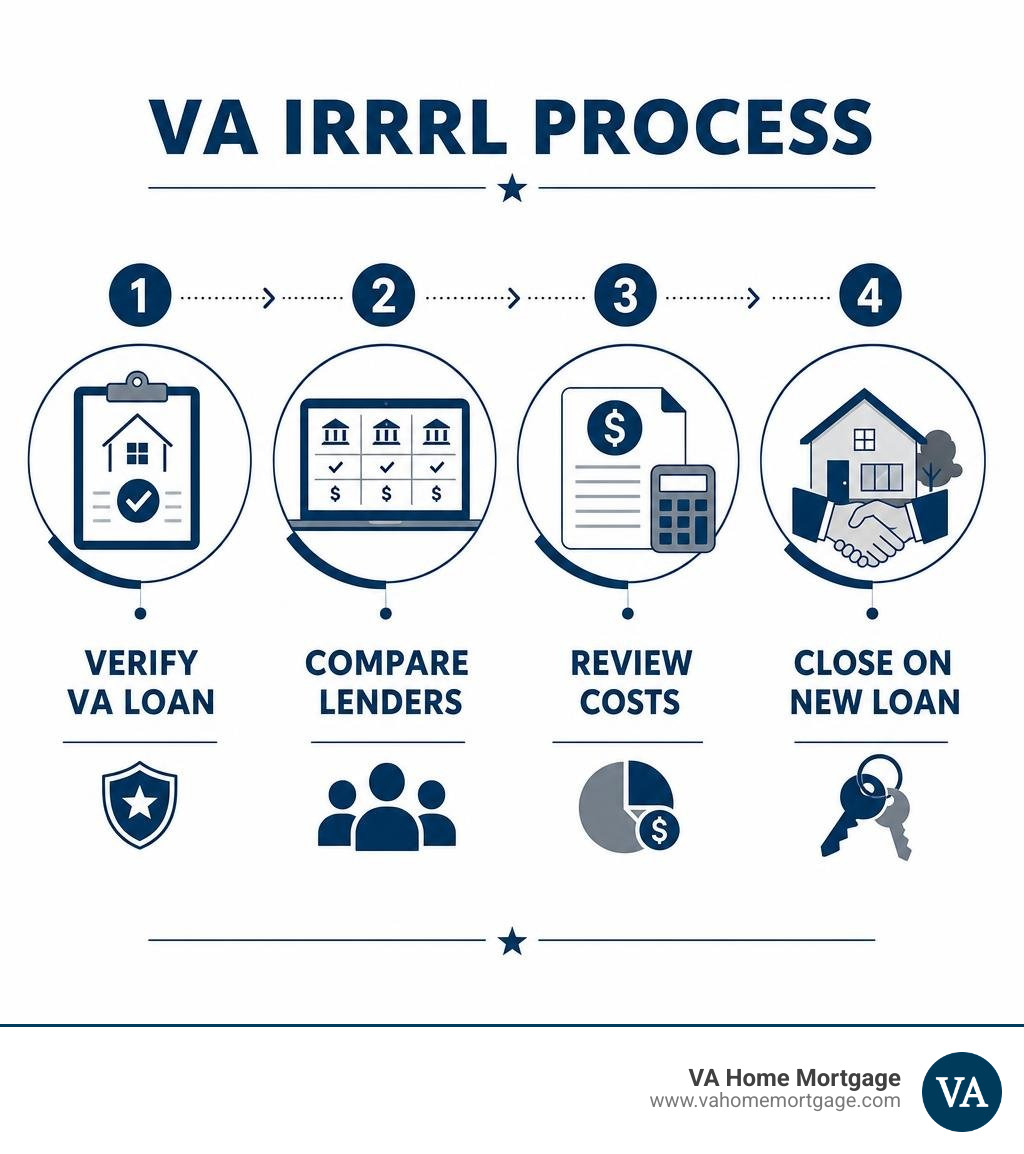
Before applying, confirm that you have an existing VA-backed loan, compare offers from several VA lenders, and review the new payment, interest rate, closing costs, and loan term. An IRRRL is not a cash-out refinance: loan proceeds must be used for the existing VA loan and eligible refinance costs. Many borrowers can finance allowable costs into the new loan rather than bringing cash to closing.
A 30-year term may keep the monthly payment manageable, but the lowest advertised rate is not always the best deal. Watch for lender fees, whether costs are being added to your balance, and unsolicited offers that promise savings without showing the full terms.
I am Dale Gremillion, a Senior Loan Officer and Producing Branch Manager with more than 25 years of residential lending experience, including VA refinance strategies. I help borrowers assess whether a 30 year VA Interest Rate Reduction Refinance Loan IRRRL supports their payment goals, closing-cost budget, and long-term plans.
Learn more about 30 year va interest rate reduction refinance loan irrrl:
- 30 year va cash out
- current 30 year va mortgage rate
- va home refinance rate
Understanding the 30 Year VA Interest Rate Reduction Refinance Loan IRRRL
When mortgage rates drop or your financial priorities change, refinancing can offer meaningful relief. The Interest Rate Reduction Refinance Loan – VA Home Loans program—often called a VA Streamline Refinance—is designed to help military homeowners reduce their interest rate and stabilize their monthly mortgage payments with minimal administrative friction.
Choosing a 30-year term on your IRRRL provides long-term payment consistency. While shortening your term builds equity faster, maintaining a 30-year amortization schedule keeps your required monthly payments as low and manageable as possible. At Capital Home Mortgage, we walk borrowers through how an IRRRL adjusts their balance, restructures their interest schedule, and provides breathing room in their household budget.
Eligibility Criteria for a 30 Year VA Interest Rate Reduction Refinance Loan IRRRL
The primary rule of an IRRRL is simple: it must be a VA-to-VA refinance. You cannot use an IRRRL to refinance a conventional, FHA, or USDA loan into a VA-backed mortgage. To qualify, you must have an existing VA loan tied to the property you intend to refinance.
In addition to having an active VA mortgage, you will need to demonstrate that the refinance offers a tangible “net tangible benefit”—meaning it must lower your interest rate and monthly principal and interest payment, or safely transition you out of an adjustable-rate product into a predictable fixed-rate loan. Borrowers can check their foundational requirements by reviewing The Complete Guide to VA Refinance Eligibility.
Occupancy and Entitlement Guidelines
Unlike an initial VA purchase loan, which requires you to move into the home as your primary residence within 60 days, an IRRRL features relaxed occupancy guidelines. To qualify, you only need to certify that you previously occupied the property as your primary home. This makes the program exceptionally beneficial for active-duty military personnel who have received Permanent Change of Station (PCS) orders and converted their former residence into a rental property.
Entitlement rules are similarly straightforward for an IRRRL. The basic entitlement available to each eligible Veteran is $36,000, and lenders will generally loan up to four times a Veteran’s available entitlement without requiring a down payment. When you execute an IRRRL, your existing entitlement simply rolls over from the old VA loan to the new one, avoiding the need to restore or recalculate unused entitlement caps.
Key Benefits of Streamline Refinancing
The primary advantage of the VA streamline program is speed and reduced paperwork. Traditional refinances require exhaustive verifications, stacks of tax transcripts, and home inspections that take weeks. The VA designed the IRRRL to bypass these hurdles for borrowers who have already proven their creditworthiness on an existing VA loan. For an overview of all VA loan options, explore The Ultimate Guide to VA Home Mortgage Refinancing.
Underwriting and Appraisal Waivers
One of the standout provisions of the IRRRL is that the Department of Veterans Affairs does not mandate a home appraisal or a standard credit underwriting package.
- No Appraisal Requirement: You do not have to pay for an appraiser to visit your home, and your loan approval does not hinge on recent neighborhood comparable home sales. Even if your local housing market has experienced a dip, you can still refinance.
- Zero Credit Underwriting Package: The VA does not require a full review of your debt-to-income (DTI) ratio, employment histories, or pay stubs. As long as you have maintained an on-time payment record on your current VA mortgage over the preceding 12 months, underwriting proceeds rapidly.
Refinancing from an ARM to a Fixed-Rate Loan
If you currently hold an Adjustable-Rate Mortgage (ARM), market fluctuations can introduce uncertainty into your financial planning. An IRRRL allows you to refinance from an ARM into a 30-year fixed-rate mortgage to permanently lock in your principal and interest payments.
When refinancing from an existing VA ARM loan to a fixed rate loan, the interest rate may increase compared to your introductory ARM rate. However, the trade-off is long-term stability: you eliminate the risk of future rate hikes. You can monitor Understanding Current 30-Year VA Mortgage Rates Today to determine whether current market conditions offer a favorable fixed lock.
Costs, Funding Fees, and Cash-Out Restrictions
Although the IRRRL is a streamlined loan, closing costs, administrative items, and government fees still apply. An IRRRL may be done with “no money out of pocket” by including all costs in the new loan balance or by structuring the loan at an interest rate that allows the lender to provide closing cost credits.
| Refinance Feature | VA IRRRL (Streamline) | VA Cash-Out Refinance |
|---|---|---|
| Appraisal Required | No (VA guideline) | Yes |
| Income Verification | Minimal / None | Full documentation |
| Occupancy Rule | Prior occupancy allowed | Must occupy as primary |
| Cash to Borrower | $0 (Strictly prohibited) | Up to 100% home equity |
| VA Funding Fee | Standard streamline rate | Higher first/subsequent use rate |
| Allowed Loan Purpose | Rate & term reduction only | Debt consolidation, cash, home improvements |
VA Funding Fee Rates and Exemptions
The VA funding fee is a statutory fee established by Congress (per Public Law 116-23) that helps sustain the VA home loan program without burdening taxpayers. For an IRRRL, the funding fee is lower than the fee charged on standard purchase or cash-out loans, regardless of whether it is your first or subsequent use of the benefit.
Borrowers can roll this fee directly into their total loan balance. Furthermore, several categories of military homeowners are completely exempt from paying the VA funding fee:
- Veterans receiving VA compensation for a service-connected disability.
- Veterans who would be entitled to receive disability compensation if they were not receiving military retirement pay.
- Active-duty service members who have been awarded the Purple Heart.
- Surviving spouses who receive Dependency and Indemnity Compensation (DIC).
Why Cash-Out is Prohibited on an IRRRL
You may NOT receive any cash from the loan proceeds of an IRRRL. The purpose of this program is solely to improve your mortgage terms, not to convert home equity into liquid funds. Every dollar disbursed must go directly toward paying off the existing VA mortgage, covering allowable closing fees, or financing energy efficiency improvements up to allowable limits.
If your financial strategy requires tapping into your accrued equity for home remodeling or high-interest debt payoffs, an IRRRL is not the correct path. Instead, look into The Ultimate Guide to a 100% Cash Out Refi to understand how a standard VA cash-out refinance functions.
Navigating Loan Terms and Choosing the Right Lender
The VA guarantees a portion of every loan, but it does not set the interest rates or lender-specific fees. Private mortgage companies establish their own pricing, underwriting overlays, and discount structures. Because of this, Veterans are strongly urged to contact several lenders because terms may vary significantly across the market.

Applying for a 30 Year VA Interest Rate Reduction Refinance Loan IRRRL vs Shorter Terms
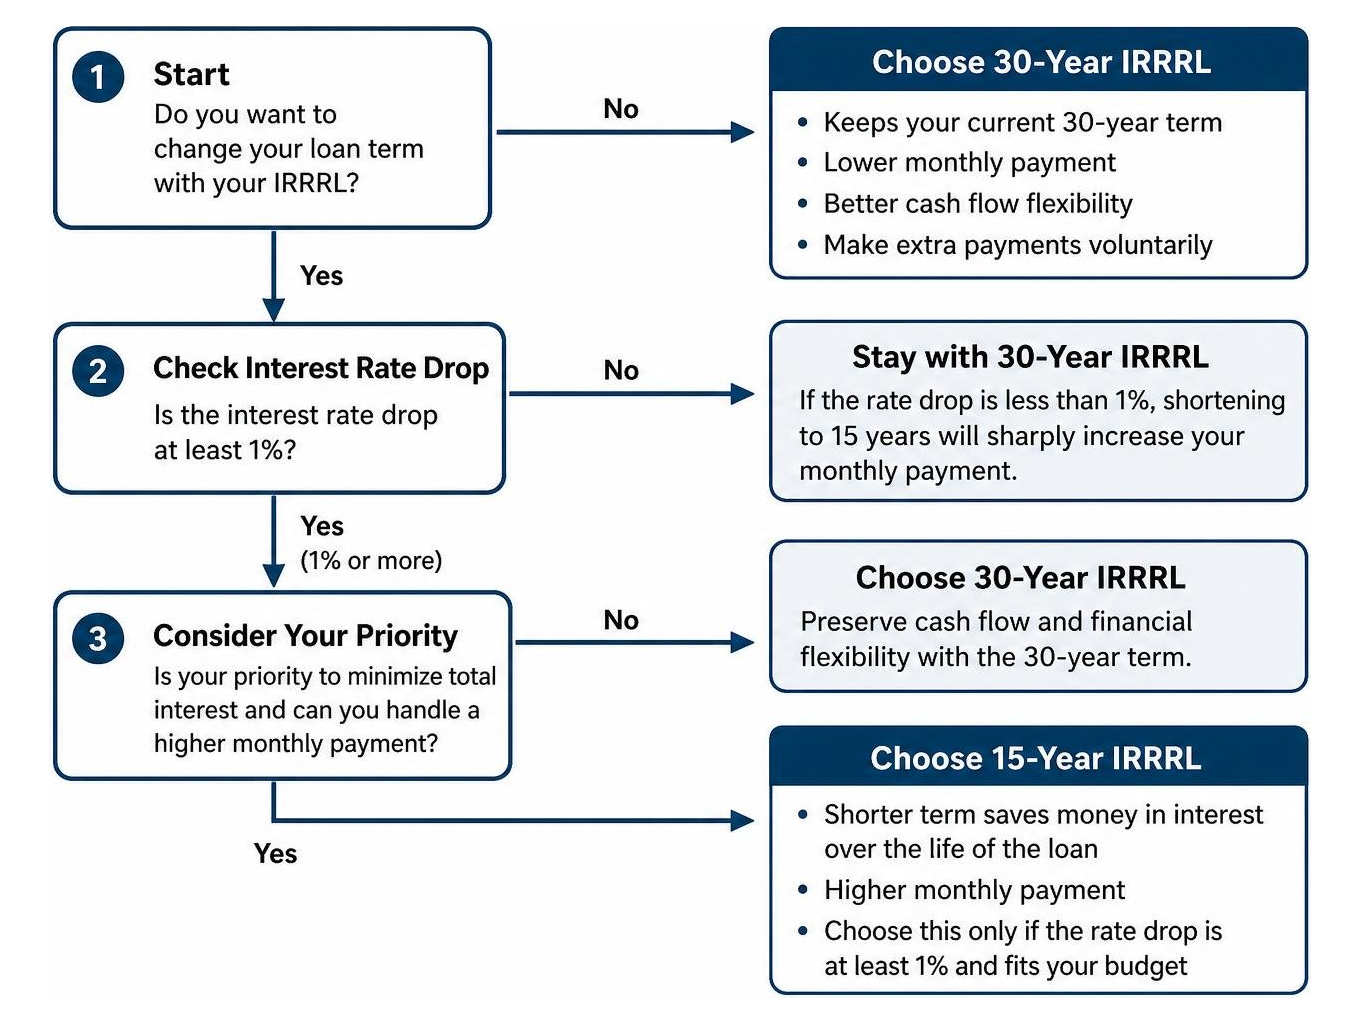
Some lenders offer IRRRLs as an opportunity to reduce the term of your loan from 30 years to 15 years, which can save money in interest over the life of the debt. However, shortening your term causes a large increase in monthly payment if the interest rate reduction is not substantial.
As a general rule, if the interest rate drop is not at least one percent (two percent is better), compressing a 30-year mortgage into a 15-year term will sharply raise your required monthly outlay. For many families, preserving cash flow with a 30-year IRRRL is the safer, more sustainable choice, allowing them to make extra principal payments voluntarily without being locked into higher mandatory obligations.
Avoiding Misleading Refinance Offers and Shopping Lenders
Because VA loan records are public information, Veterans are often targeted by aggressive direct-mail campaigns. Be cautious of unsolicited letters that mimic government agencies, advertise ultra-low teaser rates that require expensive discount points, or suggest that you can skip multiple mortgage payments without consequences.
Working directly with an established lender prevents these pitfalls. Familiarize yourself with the steps by reviewing Everything to Expect From Your VA Loan Closing Timeline. If you encounter unclear language or suspicious mailers, consider How to Contact a Local VA Home Loan Representative to verify the legitimacy of any offer before signing.
Frequently Asked Questions About VA IRRRL
Do I need a new Certificate of Eligibility for an IRRRL?
No. You do not need to request a new Certificate of Eligibility (COE). Your lender can verify your current entitlement electronically through the VA’s WebLGY portal, or you can present your existing COE or previous loan documentation to confirm your prior VA financing.
Can closing costs be rolled into the new loan?
Yes. An IRRRL can be completed with no money out of pocket. You may finance all allowable closing costs, prepaid property taxes, insurance escrows, and the VA funding fee directly into your new loan balance, provided the overall refinance meets the VA’s net tangible benefit and recoupment standards.
How does a second mortgage affect my IRRRL refinance?
If you have a second mortgage or home equity line of credit (HELOC) on the property, that lender holds a subordinate lien. For your IRRRL to close, the second mortgage holder must agree to remain in second position (a process known as subordination). Because an IRRRL cannot pay off non-VA junior liens with cash out, securing a formal subordination agreement from the secondary lender is mandatory.
Conclusion
A 30-year VA Streamline Refinance provides a fast, cost-effective path to lowering your interest rate and reducing your monthly housing expenses. With no mandatory home appraisal, no full credit re-underwriting, and the option to finance all transaction fees, the IRRRL remains one of the most practical refinancing tools available to military families.
At Capital Home Mortgage, our direct VA underwriting authority allows us to process, approve, and close your refinance in-house without unnecessary delays. Ready to review your numbers and see how much you can save? Explore our complete VA home mortgage options and get in touch with our team today.


