
VA Refinance: Two Ways to Lower Payments or Access Equity
A VA refinance replaces your current mortgage with a new VA-backed loan. It can help you lower your rate or monthly payment, switch from an adjustable-rate loan to a fixed rate, or use eligible home equity for cash.
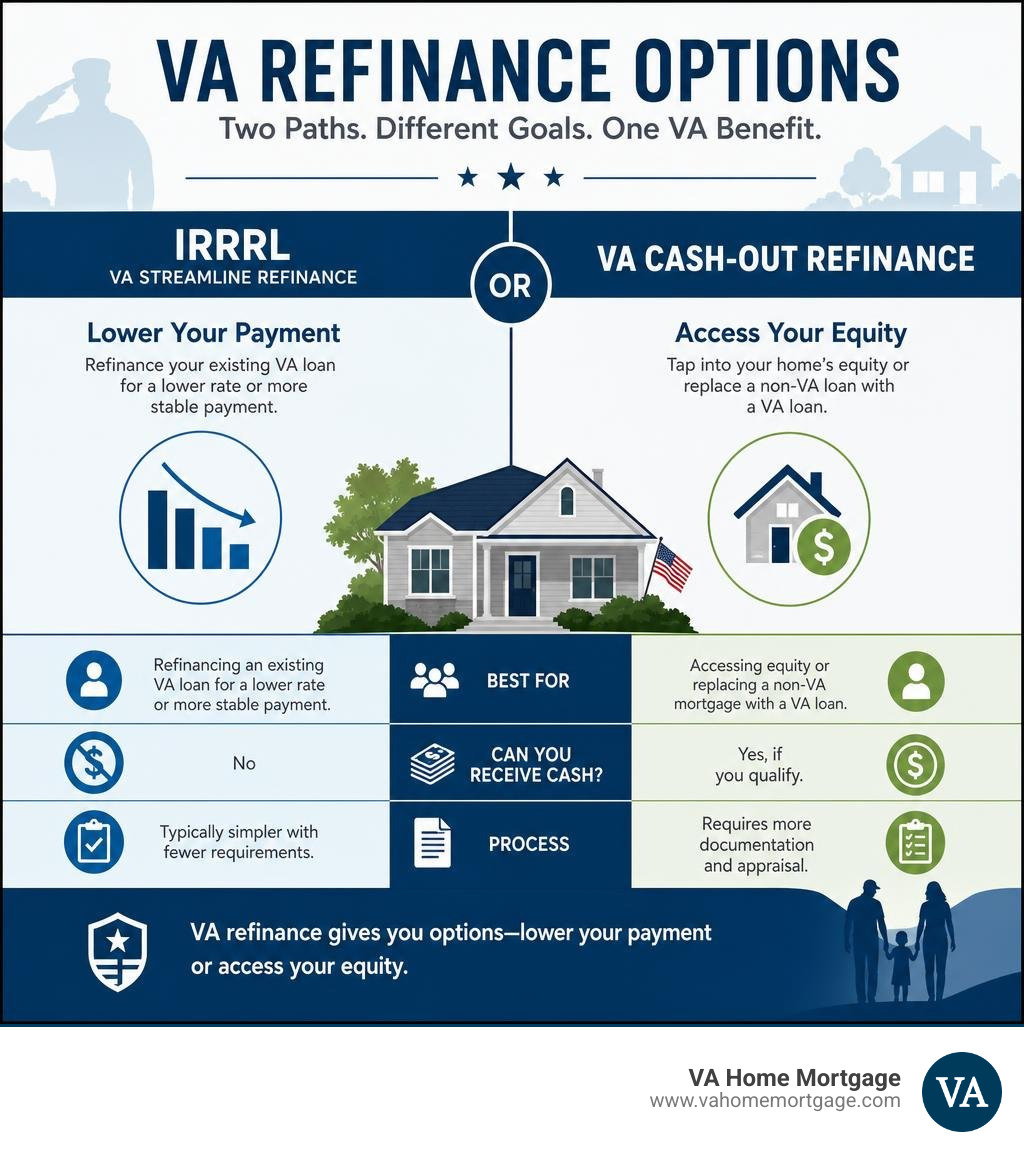
| VA refinance option | Best for | Can you receive cash? |
|---|---|---|
| IRRRL (VA Streamline Refinance) | Refinancing an existing VA loan for a lower rate or more stable payment | No |
| VA Cash-Out Refinance | Accessing equity or replacing a non-VA mortgage with a VA loan | Yes, if you qualify |
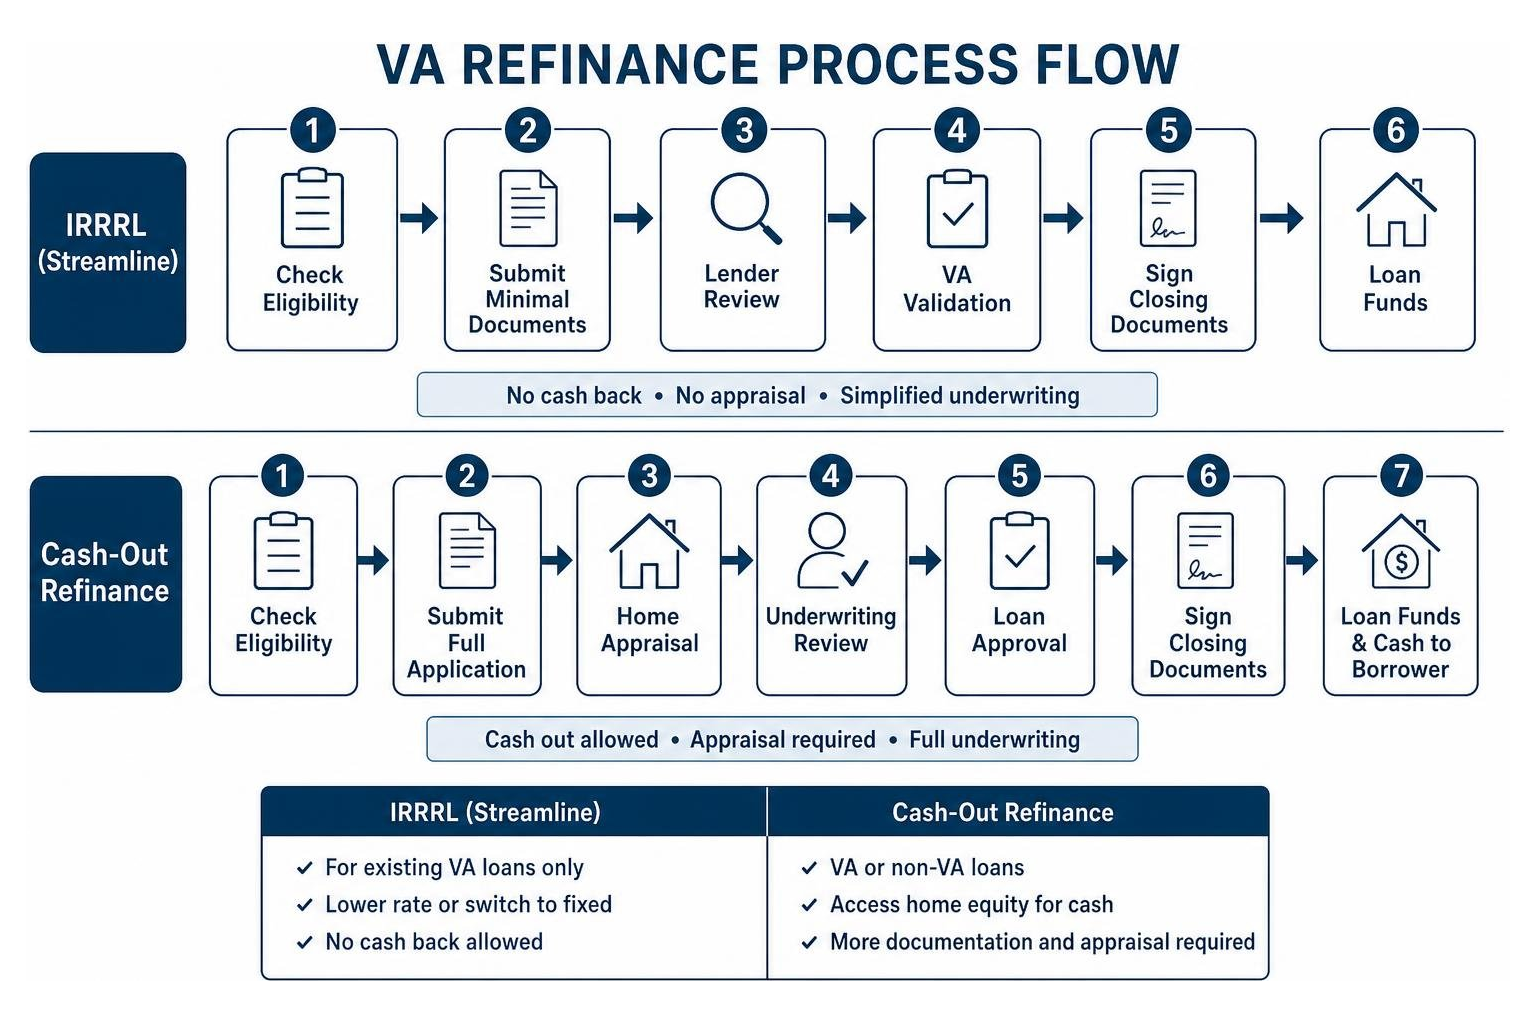
The right path depends on your current loan, how much equity you have, and what you need the new loan to accomplish. An IRRRL is generally the simpler option because it is designed for VA-to-VA refinancing and usually does not require a new appraisal or full credit underwriting package. A cash-out refinance involves more documentation and an appraisal, but it may let you consolidate debt, pay for improvements, or turn a non-VA mortgage into a VA-backed loan.
Costs still matter. VA refinancing can involve lender charges, title costs, and a one-time VA funding fee, although some borrowers are exempt. Before moving forward, compare offers carefully and make sure the savings or cash access outweighs the total cost of the new loan.
I’m Dale Gremillion, a Senior Loan Officer and Producing Branch Manager with more than 25 years in residential lending, including VA refinance and cash-out loan strategies. I help borrowers sort through eligibility, paperwork, closing costs, and loan options so they can make a clear, well-informed decision.
Understanding Your Options for a VA Refinance
When navigating home financing, understanding the full scope of your VA home loan guaranty is essential. The Department of Veterans Affairs does not lend money directly to home buyers; instead, private mortgage lenders handle the funding while the VA guarantees a portion of the loan against default. This federal backing allows us to offer eligible service members, veterans, and surviving spouses exceptional loan features, including competitive interest rates, zero down payment requirements, and no monthly private mortgage insurance (PMI).
When considering a va refinance, you are choosing between two core pathways that leverage your earned VA loan entitlement. Each option serves a distinct financial purpose, depending on whether your main goal is trimming your monthly budget or accessing equity you have built up over time. For a deeper dive into these structures, explore The Ultimate Guide to VA Home Mortgage Refinancing.
| Feature | Interest Rate Reduction Refinance Loan (IRRRL) | VA Cash-Out Refinance |
|---|---|---|
| Current Loan Requirement | Must be an existing VA mortgage | Can be a VA or conventional/FHA loan |
| Cash Proceeds | No cash back allowed at closing | Cash out permitted from home equity |
| Home Appraisal | Generally not required | Required in all cases |
| Income & Credit Underwriting | Simplified / minimal requirements | Full income, credit, and asset underwriting |
| Occupancy Requirement | Must certify prior or current occupancy | Must occupy as primary residence |
| Primary Goal | Lower rate, drop monthly payment, or switch ARM to fixed | Access home equity or convert non-VA loan |
Comparing IRRRL vs. VA Refinance Cash-Out Options
Choosing the right structure hinges on your current home loan and immediate financial goals. The Interest Rate Reduction Refinance Loan (IRRRL) is strictly a VA-to-VA transaction. If you currently hold an FHA, USDA, or conventional loan, you cannot use an IRRRL; instead, you must select a VA cash-out refinance to transition into a VA-backed mortgage.
Another core difference involves cash back. An IRRRL strictly prohibits receiving cash proceeds at closing (beyond minor administrative adjustments under $500). If your goal is consolidating debt, paying for college tuition, or completing large renovations, you will want a cash-out refinance. An IRRRL is ideal if you simply wish to lower your interest rate or transition from an adjustable-rate mortgage (ARM) to a stable, fixed-rate loan. If you own a high-value property and need expanded financing limits, check out how to Tap Equity Fast with VA Jumbo Cash Out Refinancing.
VA IRRRL Eligibility and Streamline Guidelines
The VA Streamline Refinance program—officially titled the Interest Rate Reduction Refinance Loan – VA Home Loans—is one of the most efficient mortgage products available. Because you already proved your military entitlement and financial capability when securing your initial VA mortgage, the federal guidelines for an IRRRL are designed to eliminate unnecessary paperwork.
To qualify for an IRRRL, you must meet key criteria:
- Existing VA Mortgage: The loan you are refinancing must already be a VA-backed loan.
- Prior Occupancy Certification: Unlike purchase loans that require you to move into the home immediately, an IRRRL only requires you to certify that you previously lived in the property. This flexibility makes an IRRRL accessible even if you have since been reassigned or converted the home into an investment rental.
- Subordination of Second Mortgages: If you have a second mortgage or home equity line of credit (HELOC) on the property, that lender must agree to subordinate their lien so your new va refinance remains in first position.
- Term Adjustments: You can use an IRRRL to lower your interest rate, switch from an ARM to a fixed rate, or reduce your loan term (for example, shortening a 30-year term to a 15-year mortgage).
Streamlined Processing Without Appraisal or Underwriting
What makes the IRRRL uniquely convenient is its absolute minimal processing requirement. Under federal guidelines, no home appraisal or complex credit underwriting package is required by the VA. That means you do not have to worry about minor property repairs delay closing or stressing over recent fluctuations in your home value.
Furthermore, an IRRRL can be completed with zero money out of pocket. You can roll all closing costs and the VA funding fee directly into the new loan balance, or accept a slightly higher interest rate where lender credits cover those upfront fees. Just remember: because the “no cash back rule” is strictly enforced, any money saved from rolling in costs must go entirely toward settling the existing principal balance and allowable loan charges.
VA Cash-Out Refinance Eligibility and Net Tangible Benefits
If you want to pull equity out of your home or replace a non-VA loan with a VA-backed mortgage, you will apply for a Interest Rate Reduction Refinance Loan | Veterans Affairs cash-out option. Unlike streamline refinances, a cash-out loan is a complete re-underwriting of your mortgage.
To qualify, you must meet these foundational standards:
- Certificate of Eligibility (COE): You must present a valid COE proving available loan entitlement.
- Primary Residence Occupancy: You must certify that you intend to occupy the home as your primary residence.
- Credit and Income Qualification: Lenders will verify your employment, income, credit score, and debt-to-income (DTI) ratio.
- Property Appraisal: A comprehensive home appraisal ordered through the VA portal is required to confirm the current market value and ensure the property meets minimum property requirements (MPRs).
To learn more about qualifying standards and specialized options, explore our main hub for VA Home Mortgage guidance.
Meeting the Net Tangible Benefit Requirement
To protect military families from unfair practices or unnecessary fee accumulation, federal rules outlined in Circular 26-19-5 – Exhibit A mandate that every va refinance cash-out transaction demonstrate a clear “Net Tangible Benefit” (NTB). We are required to provide side-by-side disclosure comparisons at application and prior to closing, showing exactly how the new loan improves your financial situation.
A cash-out refinance satisfies the Net Tangible Benefit requirement if it accomplishes at least one of eight specific criteria:
- It reduces your mortgage interest rate.
- It shortens your loan term.
- It reduces your monthly principal and interest payment.
- It converts an adjustable-rate mortgage (ARM) into a fixed-rate loan.
- It results in a lower Loan-to-Value (LTV) ratio.
- It replaces a short-term interim construction loan or bridge loan.
- It increases residual income for your household.
- It pays off a higher-interest debt or non-VA mortgage, freeing up overall cash flow.
In addition to demonstrating an NTB, lenders evaluate your residual income—the money left over each month after paying all fixed debt and housing expenses—and verify that your total loan amount stays within permissible guidelines, typically capped at 90 percent LTV for standard cash-out transactions.
VA Refinance Costs, Funding Fees, and Exemptions
Refinancing involves costs, and understanding these charges helps you evaluate your true break-even timeline. Standard closing costs on a va refinance include lender origination fees, title charges, recording fees, and appraisal costs (for cash-out loans). You can review current market baseline trends on our Rates Test Page.
Another key component is the VA funding fee, established under federal law to offset the program’s expense to U.S. taxpayers. Because VA loans require zero monthly mortgage insurance premiums (PMI), this one-time fee keeps the program self-sustaining.

VA Funding Fee Exemptions and Rate Factors
The standard funding fee percentage for an IRRRL is set at a low 0.50% of the total loan amount, regardless of how many times you have used your VA home loan benefit. For a cash-out refinance, the funding fee varies depending on whether it is your first time using the benefit or a subsequent use, as well as your military category (such as National Guard and Reserve members, who historically paid slightly different tier percentages).
Many veterans qualify for a complete exemption from the VA funding fee. As noted in the official VA Home Loan Guaranty Buyer’s Guide, you are exempt from paying the funding fee if you meet any of the following:
- You receive VA compensation for a service-connected disability.
- You are entitled to receive VA disability compensation but receive active-duty pay or retirement pay instead.
- You are an active-duty service member who provides documented evidence of being awarded the Purple Heart prior to or at loan closing.
- You are an unremarried surviving spouse of a veteran who died in active service or from a service-connected disability.
If you believe you qualify for an exemption, we can verify your status directly through your Certificate of Eligibility before closing.
How to Apply for a VA Refinance and Avoid Misleading Offers
Applying for a va refinance is straightforward when you gather the right documentation early. For an IRRRL, you generally only need your existing VA loan information, basic identification, and a signed occupancy statement. For a cash-out refinance, we will collect:
- Paycheck stubs covering the most recent 30-day period.
- W-2 forms for the previous two years.
- Federal tax returns for the previous two years (for self-employed borrowers or complex income streams).
- Quarterly statements for bank, asset, or retirement accounts.
For ongoing tips and advice throughout your mortgage journey, visit our Blog.
Steps to Secure Your Certificate of Eligibility for a VA Refinance
Every VA loan requires a Certificate of Eligibility (COE) to prove your entitlement status. The basic entitlement available to each eligible veteran is $36,000, which lenders utilize alongside federal loan limits to structure full-guaranty financing without down payments.
You do not need to navigate government portals alone to obtain this document. While you can request a COE directly through the online VA.gov portal, we can also retrieve your COE electronically in minutes using our direct lender administrative access. For an IRRRL, federal guidelines require the COE to be retrieved no earlier than three days prior to loan closing.
Identifying and Avoiding Misleading Refinance Solicitations
Because VA loans are backed by the federal government, military homeowners frequently receive aggressive, official-looking mailers claiming “urgent” refinance opportunities. The Consumer Financial Protection Bureau (CFPB) and the Department of Veterans Affairs issued joint Warning Orders cautioning veterans against deceptive marketing tactics.
Watch out for these red flags:
- Promises of “Skipped” Payments: Advertisements claiming you can skip two mortgage payments often fail to mention that the missed interest is simply added to your overall principal balance.
- Unrealistically Low Interest Rates: Solicitations advertising rates far below market norms often rely on mandatory, costly discount points paid out of pocket.
- Pressure Tactics: Claims that your VA loan benefits are “expiring” are false; your earned VA entitlement does not expire.
Always run a clear break-even calculation: divide your total closing costs by your projected monthly savings. If it takes 24 months to break even on costs and you plan to stay in the home for five years, refinancing makes clear economic sense. If the break-even point takes longer than you plan to stay in the home, the refinance may not be in your best financial interest.
Frequently Asked Questions About VA Refinance
Can I get cash out from my home equity using an IRRRL?
No. Federal regulations strictly prohibit borrowers from receiving cash proceeds at closing from an IRRRL. Any equity you hold remains in the home balance. The only minor exceptions permit funding up to $6,000 for allowable energy efficiency improvements (EEIs) completed in conjunction with the refinance, or minor cash-back adjustments under $500 resulting from final closing cost recalculations.
What credit score do I need for a VA loan refinance?
Officially, the Department of Veterans Affairs does not set a mandatory minimum credit score for a va refinance. Instead, the VA allows private lenders to establish their own credit overlays and underwriting standards. While automated underwriting systems evaluate your overall credit history and debt ratios, most mortgage lenders look for credit scores starting around 620 for cash-out refinances, though IRRRL approvals can often accommodate lower credit profiles.
How are closing costs handled during a VA loan refinance?
You have three primary options for managing closing costs during a va refinance:
- Roll Costs Into the Loan: With an IRRRL or cash-out refinance, allowable closing costs and the VA funding fee can be financed into the total loan balance, allowing for zero out-of-pocket payment at closing.
- Lender Credits: You can select a slightly higher interest rate where we provide a lender credit to cover all or part of your closing charges.
- Pay Out of Pocket: You can choose to pay closing fees directly at the closing table using cash or certified funds.
Conclusion
Refinancing your home should be an empowering financial step that delivers measurable savings or unlocks valuable equity. At Capital Home Mortgage, we take pride in serving military families with dedicated direct authority, streamlined processing, and in-house underwriting that speeds up your path to closing. Whether you are looking to lower your monthly payments through an IRRRL or access cash equity to achieve your broader financial goals, our experienced professionals are here to guide you through every detail.
Ready to explore your options? Reach out directly to the VA Home Mortgage Team today to review your personalized quote and secure the financing benefits you have earned.


