
Latest Benchmarks and Market Drivers for the Current 30 Year VA Mortgage Rate
When we analyze the current 30 year va mortgage rate, we must look under the hood of the broader financial markets. Mortgage rates do not move in a vacuum, nor are they set directly by the Federal Reserve. Instead, daily pricing for 30-year fixed VA loans heavily reflects trading in the secondary bond market—specifically Mortgage-Backed Securities (MBS) and the 10-year U.S. Treasury yield.
In mid-August 2026, standard daily surveys place the average 30-year fixed VA rate at 6.31% (up slightly from 6.17% in mid-August 2025). Meanwhile, specialized transaction indices like the 30-Year Fixed Rate Veterans Affairs Mortgage Index Data recorded an average rate lock of 6.297% on August 13, 2026.
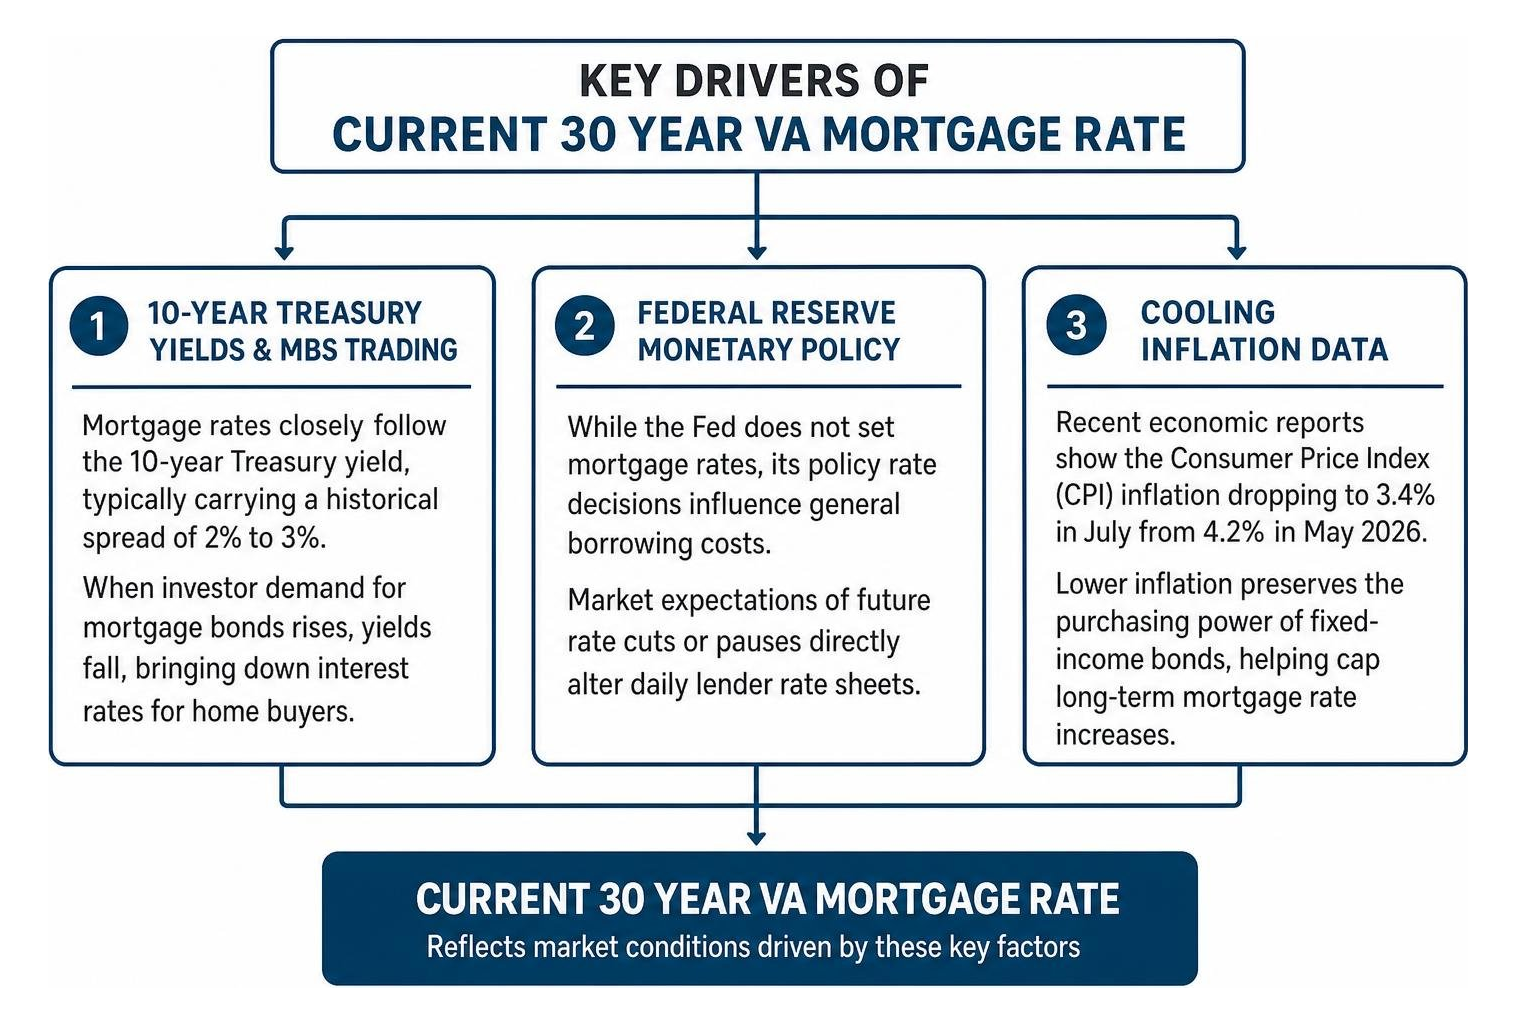
Several core macroeconomic forces are driving these rate movements:
- 10-Year Treasury Yields & MBS Trading: Mortgage rates closely follow the 10-year Treasury yield, typically carrying a historical spread of 2% to 3%. When investor demand for mortgage bonds rises, yields fall, bringing down interest rates for home buyers.
- Federal Reserve Monetary Policy: While the Fed does not set mortgage rates, its policy rate decisions influence general borrowing costs. As the Federal Reserve evaluates economic conditions, market expectations of future rate cuts or pauses directly alter daily lender rate sheets.
- Cooling Inflation Data: Recent economic reports show the Consumer Price Index (CPI) inflation dropping to 3.4% in July from 4.2% in May 2026. Lower inflation preserves the purchasing power of fixed-income bonds, helping cap long-term mortgage rate increases.
- Labor Market Shifts: A cooling jobs market combined with moderate wage growth reassures investors that hyper-inflation is waning, helping stabilize bond pricing.
How the Current 30 Year VA Mortgage Rate Compares to Standard Market Rates
One of the greatest benefits of the VA loan program is its consistently competitive pricing structure. Because the U.S. Department of Veterans Affairs guarantees a portion of every qualifying loan against default, lenders face significantly lower risk.
As a result, the current 30 year va mortgage rate typically runs 30 to 50 basis points lower than conventional 30-year fixed loans. On August 14, 2026, while the standard 30-year conventional fixed rate averaged around 6.71% to 6.75%, the 30-year VA rate averaged 6.31%. Furthermore, VA loans offer the unmatched combined benefit of zero required down payment and zero monthly Private Mortgage Insurance (PMI), keeping total monthly housing expenses well below conventional alternatives.
| Mortgage Type | Average Interest Rate | Average APR | Monthly PMI Required? | Minimum Down Payment |
|---|---|---|---|---|
| 30-Year VA Fixed | 6.31% – 6.41% | 6.45% | No | 0% |
| 15-Year VA Fixed | 5.25% – 5.60% | 5.68% | No | 0% |
| Conventional Market Benchmark | 6.69% – 6.75% | 6.82% | Yes (if down payment < 20%) | 3% – 5% |
Comparing Year-Over-Year Trends for 30-Year VA Fixed Loans
Taking a step back gives us valuable perspective on today’s pricing. In mid-August 2025, average 30-year VA rates hovered around 6.17%. Fast forward to mid-August 2026, and the average sits at 6.31%—a modest year-over-year uptick of 0.14 percentage points (14 basis points).
While rates are slightly elevated compared to last summer, the yield spread between VA loans and conventional financing remains steady. Borrowers who tracked market dips earlier in the month saw brief drops; for instance, competitive military credit unions advertised 30-year purchase rates as low as 5.63% to 5.875% in early August 2026. Tracking these yield shifts allows military buyers to capture optimal lock windows during temporary market pullbacks.
Factors Influencing Your Current 30 Year VA Mortgage Rate Quote
While national survey averages give us a great baseline, your personalized rate quote depends on specific financial and loan characteristics. Lenders evaluate several individual criteria to determine your finalized pricing:
- Credit Profile: Although VA guidelines are more flexible than conventional loans, a higher credit score generally unlocks lower rate brackets and reduced lender fees.
- Discount Points: Paying upfront discount points allows you to permanently buy down your interest rate. One point equals 1% of the loan amount and typically lowers your rate by 0.25%.
- Debt-to-Income (DTI) Ratio: A lower DTI ratio demonstrates strong cash reserves and debt management, helping you secure top-tier pricing.
- Loan Amount & Entitlement: Borrowing above standard county limits requires specialized underwriting. You can learn more about how jumbo limits work by reviewing our detailed guide on How 30-Year Fixed VA Jumbo Mortgage Rates Really Work.
- Certificate of Eligibility (COE): Verifying your service history confirms your entitlement status and determines whether you are exempt from the standard VA funding fee (such as veterans receiving service-connected disability compensation).
Choosing Between 30-Year and 15-Year VA Loans
When structuring your mortgage, selecting the right loan term is just as vital as securing a low interest rate. In today’s market, 15-year VA loans offer rates as low as 5.25%, delivering substantial interest savings over the life of the loan. However, 30-year VA loans remain the overwhelming favorite for military families due to their lower, flexible monthly payment obligations.
Pros of a 30-Year VA Loan:
- Lower Monthly Payment: Spreading principal payments over 360 months keeps your mandatory monthly housing cost manageable.
- Maximum Cash Flow Flexibility: Extra income can be directed toward savings, investments, or voluntary principal prepayments without forcing a high mandatory payment.
- Higher Purchasing Power: Lower monthly obligations make qualifying for higher home purchase prices easier.
Cons of a 30-Year VA Loan:
- Higher Interest Rate: Typically carries a rate 0.75% to 1.00% higher than a 15-year term.
- Longer Amortization: Slower initial equity accumulation and higher total interest paid over 30 years.
Pros of a 15-Year VA Loan:
- Significantly Lower Rates: Interest rates frequently run around 5.25%, saving tens of thousands of dollars in interest.
- Rapid Equity Buildup: You pay down loan principal at more than double the speed of a 30-year loan.
Cons of a 15-Year VA Loan:
- Substantially Higher Monthly Payments: Requires robust, consistent monthly income, reducing overall cash flow flexibility.
When to Lock Your Rate vs Refinance Options
Because mortgage rates fluctuate throughout the trading day, timing your rate lock is critical. Standard rate locks typically run for 30, 45, or 60 days. A 30-day rate lock is generally free of charge once your purchase contract is accepted, whereas longer locks (90 to 120 days) may require upfront lock fees or slight rate adjustments.
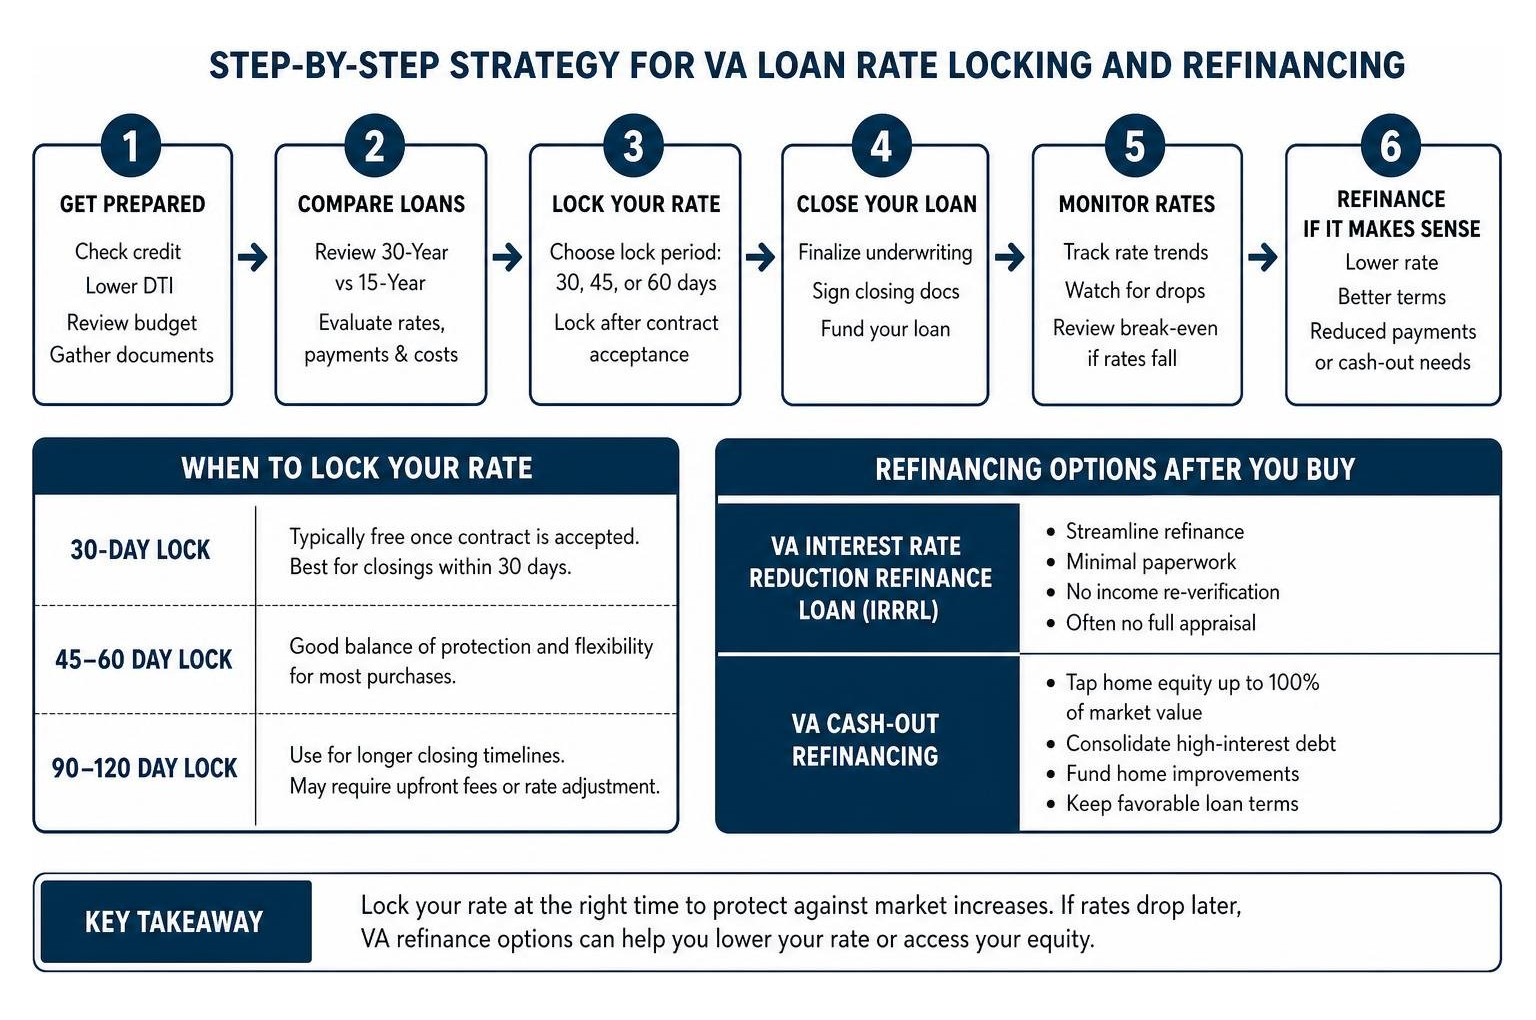
If you purchase a home today and rates decline in the future, you aren’t stuck with your original rate forever. Veterans have access to powerful streamline refinancing tools:
- VA Interest Rate Reduction Refinance Loan (IRRRL): Often called the VA Streamline Refinance, this program allows you to lower your interest rate with minimal paperwork, no income re-verification, and often no full appraisal. Read our comprehensive resource on The Ultimate Guide to VA Home Mortgage Refinancing to see how streamline refinances work.
- VA Cash-Out Refinancing: If you have accumulated home equity and want to consolidate high-interest debt or fund home improvements, a 100% cash-out refinance lets you tap your equity up to full market value. Learn more in The Ultimate Guide to a 100% Cash Out Refi.
Frequently Asked Questions About VA Loan Interest Rates
How are daily 30-year VA rates calculated?
Daily 30-year VA rates are derived from active trading in the secondary mortgage market. When lenders originate VA loans, they bundle them into Ginnie Mae (GNMA) Mortgage-Backed Securities. Investor demand for these securities establishes the baseline yield requirements daily.
Organizations like Mortgage News Daily and Bankrate survey retail lenders every morning, while financial database indices like the Optimal Blue Mortgage Market Index (OBMMI) compile automated daily transaction data directly from lender pricing engines representing over a third of all U.S. mortgage activity. You can explore daily historical surveys at Average 30 Year VA Mortgage Rate Surveys.
Why is the current 30 year va mortgage rate lower than standard market rates?
The current 30 year va mortgage rate tracks consistently lower than standard conventional rates primarily because of the government guarantee. The U.S. Department of Veterans Affairs backs 25% of the loan value against default.
Because institutional investors and mortgage lenders assume far less financial risk on a VA loan, they pass those risk savings directly to eligible military borrowers in the form of lower interest rates and narrower profit spreads.
Should veterans lock in a rate now or wait for market drops?
Trying to perfectly time the absolute bottom of a rate market is extraordinarily difficult—even for Wall Street economists. While breakeven inflation metrics (currently around 2.27%) suggest long-term stability, unexpected jobs data or geopolitical shifts can trigger sudden rate spikes.
If today’s current 30 year va mortgage rate fits comfortably within your monthly budget, locking in your rate provides guaranteed financial peace of mind. If rates drop significantly after your purchase, you can take advantage of the VA IRRRL streamline refinance to lower your rate down the road without repeating the full underwriting process.
Conclusion
Navigating today’s home financing landscape is straightforward when you understand the market drivers behind the current 30 year va mortgage rate. Averaging roughly 6.3% to 6.4% in mid-August 2026, 30-year VA loans continue to offer unmatched savings over conventional alternatives thanks to zero down payment requirements, no monthly PMI, and competitive government-backed interest rates.
At Capital Home Mortgage, we take immense pride in serving those who served our nation. As a direct VA mortgage lender with full in-house underwriting authority, our specialized team simplifies the entire financing journey—from pulling your Certificate of Eligibility to delivering fast, hassle-free loan closings. Whether you are buying your first home, upgrading for a growing family, or refinancing your existing loan, we are here to secure the low rate and loan terms you deserve.
Ready to lock in your rate or explore custom payment estimates? Explore Comprehensive Guidance at VA Home Mortgage to connect with our veteran lending specialists today!


