
Unlock Your VA Home Loan Benefit
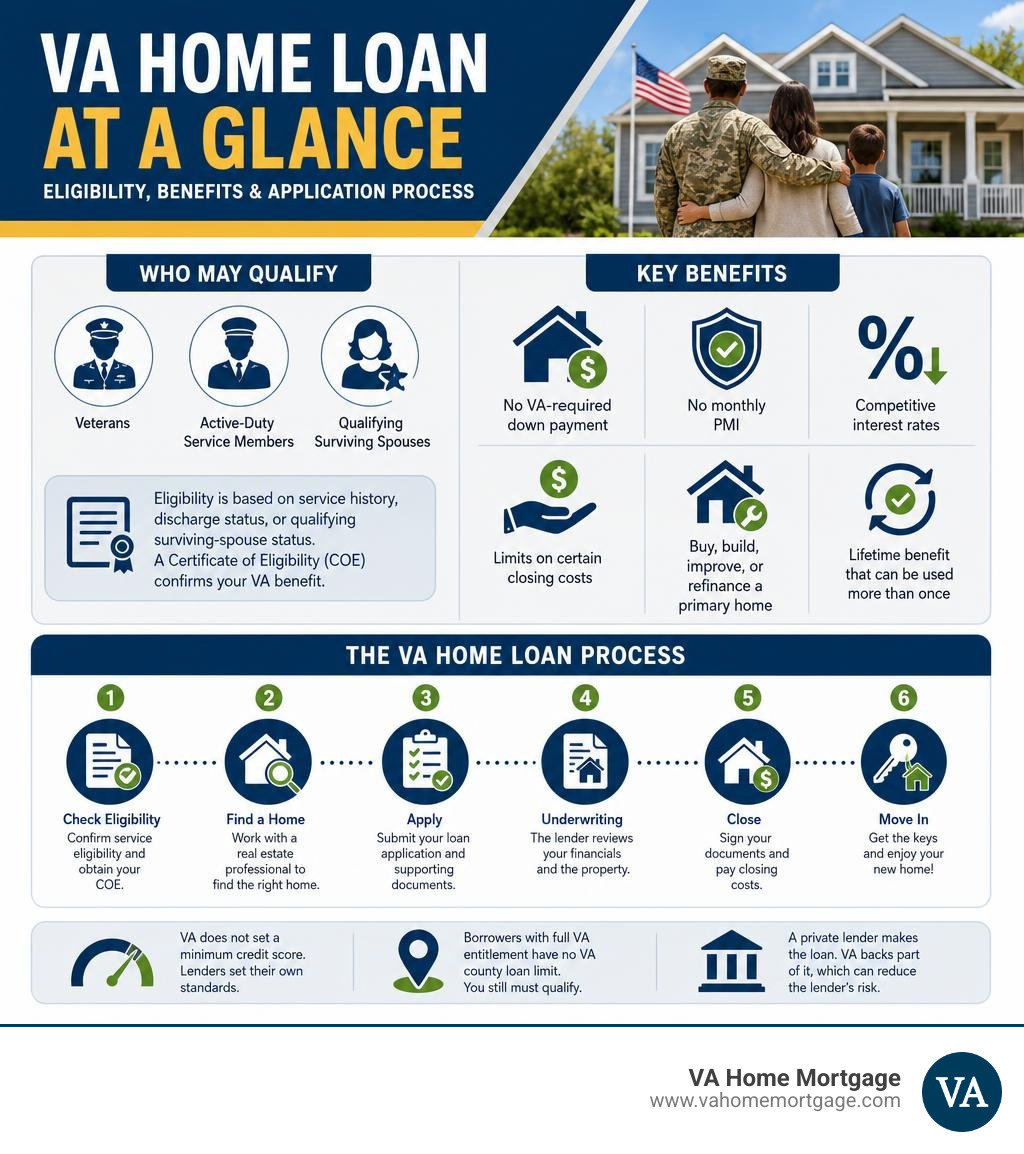
Home loans VA borrowers use are mortgages from private lenders that the Department of Veterans Affairs partially guarantees. For eligible Veterans, active-duty service members, and some surviving spouses, they can offer no VA-required down payment, no monthly private mortgage insurance (PMI), competitive rates, and limits on certain closing costs.
Here is the quick version:
- How it works: A bank, credit union, or mortgage company makes the loan. VA backs part of it, which can reduce the lender’s risk.
- Who may qualify: Eligibility is based mainly on service history, discharge status, or qualifying surviving-spouse status. A Certificate of Eligibility (COE) confirms your VA benefit.
- What you can do: Buy, build, improve, or refinance a primary home. Options include purchase loans, VA Streamline Refinances (IRRRLs), and cash-out refinances.
- What to expect: VA does not set a minimum credit score, but lenders set their own standards. Many lenders use a score near 620 as a benchmark.
- Loan limits: Borrowers with full VA entitlement have no VA county loan limit. You still must qualify based on income, credit, and the home’s value.
Created through the original GI Bill in 1944, the VA home loan program remains a lifetime benefit that eligible borrowers can use more than once. The details matter, though: entitlement, funding fees, occupancy rules, and lender guidelines can all affect your path to closing.
I’m Dale Gremillion, a Senior Loan Officer and Producing Branch Manager with more than 25 years in residential lending, including VA purchase, refinance, and cash-out financing. In this guide to home loans VA, I’ll help make the key rules, options, and next steps easier to understand.
How Home Loans VA Work and Core Benefits

When exploring home loans VA programs offer, it is helpful to understand the basic mechanics. A common misconception is that the Department of Veterans Affairs lends money directly to buyers. In reality, approved private mortgage lenders—such as mortgage companies, banks, and credit unions—issue the mortgage funds. The Department of Veterans Affairs provides a government guarantee covering a portion of the loan (typically 25% of the total loan amount) if the borrower defaults.
This federal backing significantly reduces the financial risk for lenders. Because the lender has a government safety net, we can pass along extraordinary financing terms directly to military families, including lower interest rates and flexible underwriting criteria.
Main Advantages of VA Mortgages
The perks of securing a VA-backed home loan are among the most generous in the entire housing market. When you choose to utilize home loans VA benefits, you unlock several financial advantages:
- Zero Down Payment Required: Qualifying military buyers can purchase a home with 0% down. You do not need to spend years saving up tens of thousands of dollars just to get the keys to your home.
- No Monthly Private Mortgage Insurance (PMI): Conventional loans require monthly PMI if you put down less than 20%, and FHA loans charge ongoing Mortgage Insurance Premiums (MIP). VA loans completely eliminate monthly mortgage insurance fees, saving borrowers hundreds of dollars every month.
- Competitively Low Interest Rates: Because of the federal guarantee, VA interest rates consistently rank among the lowest available in the mortgage industry.
- Strict Caps on Closing Costs and Fees: The VA restricts the types and amounts of closing fees lenders can charge military buyers. Furthermore, sellers can contribute up to 4% of the purchase price in seller concessions to help cover closing costs and prepaid items.
To dive deeper into the core structure of these government-backed programs, review the official VA Home Loans portal.
Credit Scores and Lender Underwriting Standards
A unique feature of the VA loan program is that the Department of Veterans Affairs itself does not set a minimum required credit score. Officially, the VA requires that a applicant possess satisfactory credit history and sufficient income to cover monthly expenses.
However, because private lenders issue the actual funds, individual lenders establish their own underwriting guidelines, known as “lender overlays.” Across the lending industry, many institutions look for a minimum credit score benchmark around 620. At Capital Home Mortgage, as a direct VA lender with in-house underwriting, we evaluate the entire financial picture rather than relying strictly on an automated cutoff.
In addition to credit scores, lenders evaluate your Debt-to-Income (DTI) ratio. While conventional mortgages enforce strict DTI caps, VA underwriting looks holistically at residual income—the money remaining in your bank account each month after paying all fixed expenses and family obligations. This ensures military households can comfortably afford their living arrangements.
Service Eligibility Requirements and Entitlement Rules

Eligibility for home loans VA programs depends on your military service history, active-duty duration, service era, and character of discharge.
Military Service Criteria Overview
- Active Duty Service Members: Eligible after serving 90 continuous days of active duty.
- Veterans (Wartime vs. Peacetime): Requirements vary based on when you served. Wartime eras generally require 90 consecutive active days, while peacetime eras require 181 continuous active days. For those who enlisted after September 7, 1980 (or officers after October 16, 1981), the general standard is 24 continuous months of service or the full period for which you were called to active duty (minimum 90 days).
- National Guard Members: National Guard personnel qualify after completing at least 90 days of active service, including at least 30 consecutive days under Title 32, Sections 316, 502, 503, 504, or 505. Alternatively, Guard members with 6 creditable years of service also qualify.
- Reserve Members: Reservists meet criteria after completing 6 creditable service years or meeting active-duty mobilization thresholds.
- Surviving Spouses: Unremarried surviving spouses of Veterans who died in the line of duty or from a service-connected disability may be eligible. Additionally, spouses who remarry on or after age 57 (and after December 16, 2003) may retain eligibility.
Discharge status must generally be under honorable conditions. If an applicant received an Other Than Honorable (OTH) discharge, they can request a Character of Discharge review or apply for a discharge upgrade through the Department of Veterans Affairs.
Applying for Home Loans VA and Obtaining Your COE
The official first step in the VA homebuying process is obtaining your Certificate of Eligibility (COE). The COE acts as proof to lenders that you have satisfied the required military service criteria.
You can secure your COE in three ways:
- Through Your Lender: As a direct VA mortgage lender, we can pull your COE instantly through the online portal using your military identification details.
- Online via VA.gov: You can log into your personal online account and request your COE directly.
- By Mail: Complete VA Form 26-1880 (Request for a Certificate of Eligibility) and mail it to the designated Regional Loan Center, though processing takes longer.
For exact service era breakdowns and forms, consult the official guide on Eligibility For VA Home Loan Programs.
Managing Entitlement Reuse and Limits on Home Loans VA
Your VA entitlement is the precise dollar amount the government guarantees on your mortgage. Thanks to the Blue Water Navy Vietnam Veterans Act of 2019, buyers with full entitlement (first-time users or those who have fully restored entitlement) face no VA loan limits. You can borrow as much as a lender approves based on your income and credit without paying any down payment.
If you have partial entitlement—meaning you currently have an active VA loan on a primary home or previously defaulted on a VA loan without full repayment—county loan limits apply when purchasing an additional property.
Because the VA home loan is a lifetime benefit, you can reuse it multiple times. If you sell a property purchased with a VA loan and pay off the mortgage balance in full, your full entitlement can be completely restored. Furthermore, veterans are granted a one-time entitlement restoration allowing them to restore full entitlement after paying off a VA mortgage in full, even if they choose to retain ownership of the original property.
To learn how high-balance home purchases work without conventional restrictions, check out our detailed guide on How 30 Year Fixed VA Jumbo Mortgage Rates Really Work.
Exploring VA Loan Options and Mortgage Types

Whether you are looking to buy a move-in ready home, build from the ground up, or optimize an existing loan, home loans VA programs offer tailored solutions for every stage of property ownership.
VA Purchase Loans and Construction Mortgages
A standard VA purchase loan allows you to buy single-family homes, approved condominium units, manufactured homes, or multi-family properties (up to 4 units, provided you occupy one unit as your primary residence).
When submitting an offer on a home using a VA purchase loan, military buyers benefit from essential contractual safeguards:
- The VA Escape Clause: Every VA purchase contract includes mandatory language stipulating that if the VA appraisal comes in lower than the agreed-upon purchase price, the buyer can walk away from the transaction without forfeiting their earnest money deposit.
- Reconsideration of Value (ROV): If an appraisal returns lower than expected, buyers and their real estate agents can request an ROV by presenting recent comparable home sales to justify the higher contract price.
- Minimum Property Requirements (MPRs): Mandatory VA property appraisals evaluate both market value and safety standards, ensuring the structural integrity, roof condition, plumbing, and heating systems meet safe living standards.
If you prefer building a custom property from scratch rather than buying an existing house, specialized construction options combine land purchase and building costs into a single loan. Explore our guide on Texas VA One Time Close Construction Loans to see how a streamlined single closing works.
VA Refinance Programs: IRRRL and Cash-Out
If you already hold a mortgage, refinancing can help you secure better interest rates or unlock property equity:
- Interest Rate Reduction Refinance Loan (IRRRL): Also known as a VA Streamline Refinance, an IRRRL allows you to refinance an existing VA loan into a lower interest rate with minimal paperwork. An IRRRL does not require a new Certificate of Eligibility (COE), structural appraisal, or extensive underwriting checks. Read more in The Ultimate Guide to VA Home Mortgage Refinancing.
- VA Cash-Out Refinance: Unlike an IRRRL, a VA Cash-Out Refinance allows you to replace any mortgage type (VA, conventional, or FHA) with a new VA loan while tapping into home equity. You can extract cash to consolidate high-interest debt, pay for education, or finance home renovations up to 100% of the home’s value. Discover the full details in The Ultimate Guide to a 100% Cash Out Refi.
Specialized VA Housing Grants and Direct Loans
The Department of Veterans Affairs also maintains specialized programs for specific buyer needs:
- Native American Direct Loan (NADL) Program: Provides direct home financing to Native American Veterans or Veterans married to Native Americans to purchase, build, or renovate homes located on federal trust land.
- Specially Adapted Housing (SAH) and Special Housing Adaptation (SHA) Grants: Non-repayable grant funds awarded to Veterans with severe service-connected disabilities. These grants enable home modifications—such as installing wheelchair ramps, widening doorways, or rebuilding accessible bathrooms—ensuring independent living.
Navigating VA Funding Fees, Occupancy Rules, and Hardship Support
Understanding fee structures, occupancy requirements, and default assistance ensures a seamless, worry-free homebuying journey.
Understanding VA Funding Fees and Exemptions
Because home loans VA programs do not charge monthly PMI, Congress established a one-time government fee known as the VA Funding Fee. This fee directly offsets the cost of operating the guaranty program for future generations of service members.
The funding fee percentage depends on your down payment size, whether it is your first time using the benefit, and the loan type. Borrowers can pay the fee in cash at closing or roll the fee directly into their total loan balance.
Standard VA Funding Fee Schedule Overview
| Loan Purpose & Down Payment Amount | First-Time Use Fee % | Subsequent Use Fee % |
|---|---|---|
| Purchase Loan: 0% Down Payment | 2.15% | 3.30% |
| Purchase Loan: 5% to 9.99% Down Payment | 1.50% | 1.50% |
| Purchase Loan: 10% or More Down Payment | 1.25% | 1.25% |
| Cash-Out Refinance Loan | 2.15% | 3.30% |
| IRRRL (Streamline Refinance) | 0.50% | 0.50% |
| Manufactured Home Loans (non-lot) | 1.00% | 1.00% |
Funding Fee Exemptions
Many Veterans qualify for a complete exemption from the VA funding fee. You are exempt if:
- You receive VA compensation for a service-connected disability.
- You are entitled to receive VA disability compensation but receive active-duty retirement pay instead.
- You are an active-duty service member awarded the Purple Heart.
- You are an eligible surviving spouse receiving Dependency and Indemnity Compensation (DIC).
Review complete regulatory rules in the official VA Home Loan Guaranty Buyer’s Guide.
Occupancy Requirements and Exception Rules
VA mortgages are exclusively designed for primary residences—they cannot be used to purchase investment properties, commercial spaces, or vacation homes.
Key occupancy rules include:
- 60-Day Occupancy Rule: Borrowers are required to move into the home within 60 days of closing the mortgage.
- Spouse and Dependent Occupancy: If an active-duty service member is deployed or stationed elsewhere, their spouse or dependent child (certified by an attorney or legal guardian) can satisfy the occupancy requirement by living in the property.
- Retirement Exceptions: Retiring service members applying for a VA loan within 12 months of separation can delay occupancy for up to 12 months with official retirement documentation.
Default Prevention and Loan Technician Assistance
If unexpected financial hardship strikes—such as sudden medical expenses or loss of employment—the Department of Veterans Affairs provides built-in default prevention assistance to keep military families in their homes.
VA loan technicians offer dedicated mortgage counseling, loan modification options, repayment plans, and forbearance arrangements. If you encounter payment difficulties, call the dedicated VA loan technician hotline directly at 877-827-3702.
To speak with a qualified representative about navigating current mortgage obligations, see How to Contact a Local VA Home Loan Representative.
Frequently Asked Questions About VA Mortgages
Can I use a VA loan to buy a property in a foreign country?
No. VA home loans cannot be used to purchase property in a foreign country. Under federal guidelines, properties purchased with a VA-backed mortgage must be physically located within the United States, its official territories, or possessions (such as Puerto Rico, Guam, the U.S. Virgin Islands, American Samoa, and the Northern Mariana Islands).
What happens if I go through a divorce while on a VA home loan?
Divorce can complicate occupancy and entitlement restoration. If a Veteran and civilian spouse divorce, the civilian spouse cannot remain in the home on the existing VA loan unless the Veteran remains on the mortgage or the home is refinanced into a conventional mortgage.
Furthermore, if the non-Veteran ex-spouse remains in the home under the original VA mortgage, the Veteran’s VA entitlement remains tied to that property until the loan is fully paid off, preventing the Veteran from restoring full entitlement for a new home purchase.
Do seller concessions cover all closing costs on a VA loan?
VA rules permit home sellers to contribute up to 4% of the total purchase price in seller concessions. These concessions can cover traditional buyer closing costs, prepaid property taxes and insurance, buy-down points, or even pay off outstanding credit card debt or judgments at closing. However, standard lender closing costs (such as loan origination fees) are evaluated separately from this 4% cap.
Conclusion
Securing a mortgage backed by the Department of Veterans Affairs is one of the most powerful financial benefits earned through military service. With zero down payment requirements, no monthly mortgage insurance, competitive interest rates, and lifetime benefit reuse, home loans VA programs clear a direct path to sustainable homeownership for military families.
At Capital Home Mortgage, as a direct VA mortgage lender with full in-house underwriting, we take immense pride in serving those who served our nation. Whether you are buying your very first home, building a new house, or refinancing your current mortgage to lower monthly costs, our experienced team simplifies every step of the journey.
Ready to take your next step? Connect with our experts through our VA Home Mortgage Team page or explore complete home financing guides on our main VA Home Mortgage Solutions portal today!


