
How a VA Mortgage Loan Specialist Secures Your Military Housing Benefits
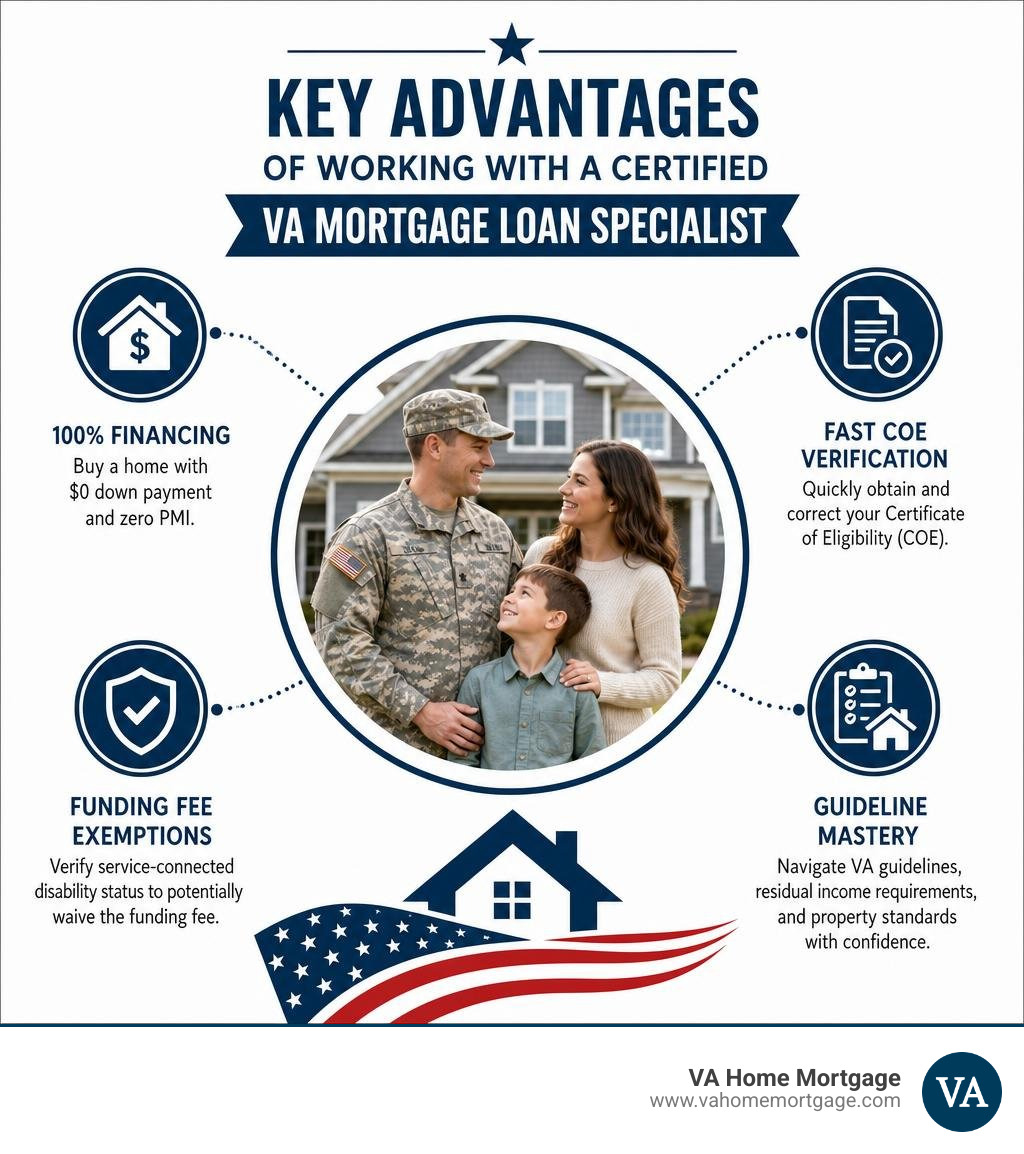
A VA mortgage loan specialist is a lending professional trained specifically in Department of Veterans Affairs financing rules, underwriting guidelines, and military benefits. Working with a dedicated specialist ensures you maximize the unique perks you earned through your service, including:
- 100% Financing: Purchase a home with $0 down payment and zero monthly private mortgage insurance (PMI).
- Fast COE Verification: Rapidly retrieve and correct your Certificate of Eligibility (COE) to confirm your available entitlement.
- Funding Fee Exemptions: Verify service-connected disability status to potentially waive the VA funding fee entirely.
- Guideline Mastery: Navigate strict VA residual income requirements and property appraisal standards without unnecessary delays.
Qualifying for a home loan shouldn’t feel like a battle against red tape.
I’m Dale Gremillion, a Senior Loan Officer with over 25 years of mortgage experience helping military families navigate complex financing as a dedicated va mortgage loan specialist. In this guide, we’ll cover everything you need to know about choosing the right expert, streamlining your paperwork, and securing the best terms on your next home.
What Does a VA Mortgage Loan Specialist Do for Military Borrowers?
Navigating the mortgage market can feel overwhelming, but military buyers have access to one of the most powerful financial vehicles in the country: the VA-guaranteed home loan. Established back in 1944, this program has helped millions of service members, Veterans, and eligible surviving spouses build long-term generational wealth.
However, taking full advantage of these benefits requires more than just filling out a generic loan application. It requires a partner who understands the distinct nuances of military life. By unlocking your military housing benefits with home loans va, you can avoid the costly mistakes common to standard retail financing.
A dedicated loan specialist provides essential support across several key areas:
- Determining Entitlement and Fee Waivers: Your specialist calculates your available entitlement (basic vs. bonus/tier two) to ensure you can purchase with zero down payment—even in high-cost housing markets. They also check your disability rating to see if you qualify for an exemption from the mandatory VA funding fee.
- Mastering Residual Income Thresholds: While conventional and FHA loans lean heavily on strict debt-to-income (DTI) ratios, VA underwriting prioritizes residual income—the discretionary cash left over each month after paying all major living expenses and taxes. An expert structures your debt profile to meet regional residual requirements easily.
- Structuring Tailored Financing Solutions: Whether you need a standard purchase loan, a streamlined Interest Rate Reduction Refinance Loan (IRRRL), or a full equity cash-out, your specialist tailors loan structures to your specific financial goals.
How a VA Mortgage Loan Specialist Navigates Underwriting and COE Verification
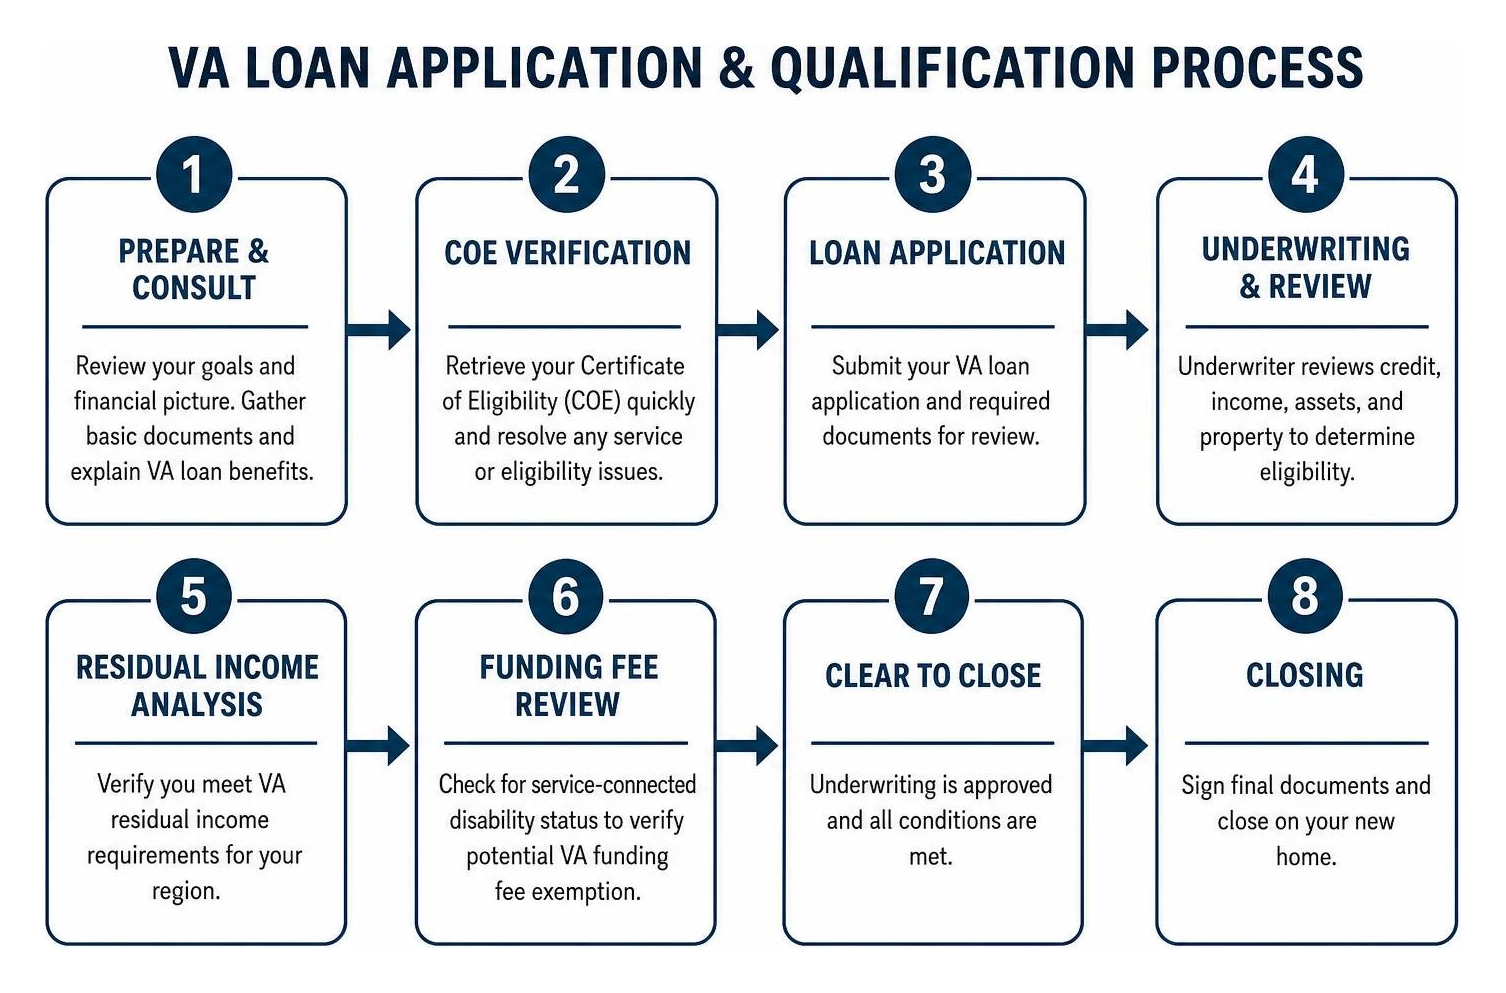
A major roadblock for many Veterans using unspecialized lenders is delays in obtaining and verifying military service documentation. An experienced loan officer connects directly to the VA’s administrative portals—such as WebLGY and LGYHub—to pull your Certificate of Eligibility (COE) within minutes.
When discrepancies arise—such as missing discharge papers (DD-214), points statements for National Guard or Reserve members, or unrecorded service-connected disability ratings—a specialist knows how to submit formal correction packages through official VA channels. Working with the top VA mortgage lenders to find the best for you means partnering with in-house underwriters who hold direct VA endorsement authority. This eliminates the middleman, speeds up approvals, and keeps your transaction moving smoothly toward closing day.
Managing Appraisals and Reconsiderations of Value with a VA Mortgage Loan Specialist
The Department of Veterans Affairs maintains strict Minimum Property Requirements (MPRs) to protect military buyers from unsafe or structurally deficient housing. VA-assigned fee appraisers evaluate properties to confirm they are safe, sound, and sanitary.
When an appraisal flags issues or comes in lower than the agreed purchase price, an inexperienced lender might advise you to walk away. In contrast, an experienced loan specialist knows how to step in and resolve the issue:
- Tidewater Protocol: When an appraiser suspects the valuation will fall short of the purchase contract, they invoke the “Tidewater” procedure. Your specialist works alongside your real estate agent to provide recent, verifiable comparable sales within 48 hours to support the contract price.
- Reconsideration of Value (ROV): If the final appraisal still comes in low, your specialist prepares a formal ROV package with the local Regional Loan Center (RLC), challenging the report with detailed market data.
- Condo Approvals and Case Transfers: If you are buying a condominium that is not yet on the VA-approved list, your specialist submits the property documentation to the VA for project approval. They can also seamlessly manage appraisal case transfers if you switch lenders mid-transaction.
Specialized VA Lending Programs and Accessibility Grants
Beyond standard home purchase loans, the Department of Veterans Affairs administers several direct programs and housing grants tailored to specific military service situations:
- Specially Adapted Housing (SAH) Grants: Designed for Veterans with specific, permanent service-connected disabilities, SAH grants help build, remodel, or adapt homes for barrier-free living (e.g., installing wheelchair ramps, widening doorways, or adding specialized roll-in showers).
- Special Home Adaptation (SHA) Grants: Aimed at service members with qualifying mobility or sight impairments, these grants assist in adapting existing homes to improve independent daily living.
- Native American Direct Loans (NADL): The NADL program provides direct VA financing to eligible Native American Veterans (or Veterans married to Native American non-Veterans) purchasing, constructing, or improving homes located on Federal Trust Land.
| Program Feature | Standard VA Purchase Loan | Native American Direct Loan (NADL) | Specially Adapted Housing (SAH) |
|---|---|---|---|
| Loan/Grant Type | Private Lender (VA-Guaranteed) | Direct Government Loan (VA) | Direct Grant (Non-repayable) |
| Down Payment | $0 Down Payment | $0 Down Payment | N/A (Grant Funding) |
| Property Location | Any standard residential parcel | Approved Federal Trust Land | Qualifying primary residence |
| Key Eligibility | Qualifying active duty or Veteran service | Eligible Native American Veteran on trust land | Specific service-connected disability |
| Primary Use | Home purchase, build, or refinance | Purchase, build, or renovate trust land home | Home modification for accessibility |
How to Contact VA Loan Representatives and Utilize ServiceNow
While your private mortgage specialist handles loan origination, processing, and underwriting, you or your lender may occasionally need direct administrative support from Department of Veterans Affairs personnel.
The primary system for submitting inquiries to the VA Home Loan program is the ServiceNow Customer Service Management (CSM) portal.
Using ServiceNow, Veterans, lenders, appraisers, and loan servicers can submit, track, and resolve questions regarding COE corrections, prior approval requests, and policy exceptions. Authenticated users access the system using AccessVA credentials and ID.me login accounts, while guest portals accommodate standard inquiries.
For general questions, review our step-by-step breakdown on how to contact a local VA home loan representative.
Official contact details include:
- Toll-Free Phone Support: (877) 827-3702 (Available Monday through Friday, 8:00 AM – 6:00 PM EST)
- NADL Direct Assistance: (888) 349-7541 (TTY: 711) or via email at
NADL@va.gov - Lender Portal Support: Inquiries can be routed through ServiceNow CSM or by contacting
VIP.VBACO@va.gov
Mortgage Servicing, Refinancing, and Loss Mitigation Support
Your relationship with VA financing does not end once you receive the keys. Over the life of your mortgage, your financial needs and market conditions will change.
When interest rates drop or you want to tap into your home’s equity, a specialist can guide you through refinancing solutions:
- Interest Rate Reduction Refinance Loan (IRRRL): A streamlined program designed to lower your monthly interest rate with minimal paperwork, no mandatory appraisal, and reduced closing costs. Learn all your options in the ultimate guide to VA home mortgage refinancing.
- VA Cash-Out Refinance: Access up to 100% of your home’s appraised value to consolidate high-interest debt, fund home improvements, or cover major life expenses.
Understanding the process beforehand helps you stay ahead of every step outlined in everything to expect from your VA loan closing timeline.
What if You Face Financial Hardship?
If unexpected emergencies, health challenges, or job changes make it difficult to pay your mortgage, the VA provides dedicated loan servicing specialists to help protect your home from foreclosure.
Contact your mortgage servicer immediately and notify the VA Regional Loan Center. Available loss mitigation options include:
- Repayment Plans: Spreading past-due amounts over regular monthly installments.
- Special Forbearance: Temporarily pausing or reducing payments during short-term financial distress.
- Loan Modification: Adding unpaid balances back to the loan principal and extending terms to achieve an affordable payment.
- Veterans Crisis Line Support: For service members experiencing profound emotional or financial distress, call 988 (Press 1) or text 838255 for immediate, confidential assistance.
Frequently Asked Questions About VA Loan Representation
What is the fastest way to get answers about the VA-guaranteed home loan program?
The fastest route for Veterans, lenders, and appraisers to receive direct administrative answers is via the VA’s online ServiceNow CSM Portal. You can log in using ID.me or AccessVA credentials to submit support tickets, track active cases, and receive formal responses from VA regional technicians.
How do I contact official VA home loan support by phone?
You can reach VA home loan representatives toll-free at (877) 827-3702, Monday through Friday, from 8:00 AM to 6:00 PM Eastern Standard Time. This line connects you with specialists who can answer questions regarding your eligibility, entitlement balance, or loan servicing options.
What should a Veteran do when experiencing difficulty making mortgage payments?
If you are struggling to make payments, contact your loan servicer immediately and inform them of your military Veteran status. Then, call the VA Loan Servicing team at (877) 827-3702 to request loss mitigation assistance. VA loan specialists can intervene, coordinate with your lender, and help structure loan modifications or forbearance plans to help you avoid foreclosure.
Conclusion
Securing a VA loan is one of the most rewarding financial milestones of your military journey. But navigating the specific property guidelines, entitlement calculations, and underwriting details requires a specialist who understands the process inside and out.
At Capital Home Mortgage, we take pride in serving those who served our nation. As a dedicated direct lender with in-house underwriting, we provide fast, clear answers and eliminate unnecessary closing delays. Whether you are buying your first home or refinancing an existing mortgage, connect with the VA Home Mortgage Team today to get the guidance and savings you deserve.


